The best accounts receivable software for UK non-profits in 2026 is Paidnice, for a charity on Xero or QuickBooks Online that needs one rule for funders and another, with interest, for trading customers. Chaser, Kolleno and Satago complete the four, compared on how each chases funders and trading customers under different rules, and on price. Prices from £25 a month.
| Tool | Fits |
|---|---|
| Paidnice | A charity on Xero or QuickBooks Online whose approved policy needs one rule for funders and another, with interest, for trading customers |
| Chaser | A larger charity with a named credit controller that wants separate chase schedules and Creditsafe checks on its trading debtors |
| Kolleno | A larger non-profit on NetSuite or Sage Intacct that needs to allocate grant tranches and bulk public-sector remittances |
| Satago | A Sage 50 or Xero charity waiting on local-authority payers that wants invoice finance from the same provider as its chasing |
None of the four is built for the charity sector, so every entry here is judged on fit rather than on a sector badge.
Related guides: the best credit control software UK, how to chase overdue invoices, how to choose credit control software for Xero
The Xero Small Business Insights figures put UK manufacturing at 37.9 days and hospitality at 16.7, around an average of 29.3 days to be paid and 8.3 days past due, both marginally better than the 29.6 and 9.2 recorded a year before.
How this list was put together
This list helps a UK charity or non-profit chase funders and trading customers under different rules, on Xero, QuickBooks Online or Sage.
| What we checked | Where the evidence came from |
|---|---|
| Chasing segmentation: a funder on one rule, a trading customer on another | Vendor workflow and customer group documentation |
| Late fee grain and statutory interest under the Late Payment of Commercial Debts (Interest) Act 1998 | Vendor help pages on fees and interest |
| Statements, payment plans and a portal | Vendor feature pages |
| Credit checks and invoice finance | Vendor product pages |
| Published from-price | Vendor pricing pages, in the currency each vendor prints |
| Rating and review count | The Xero App Store or G2 |
Which accounts receivable software suits a non-profit?
 |
 |
 |
 |
|
|---|---|---|---|---|
| Best for | Xero or QuickBooks Online charity with a rule per payer group | Charity with a credit controller and a trading subsidiary | Larger non-profit on NetSuite or Sage Intacct needing cash application | Sage 50 or Xero charity wanting credit reports and invoice finance |
| Revenue fit | Any size up to 50,000 invoices a year | Compact under £4m, Core from £4m, Complete to £100m | Under £1m on BusinessPay, tiers to £1bn and above | Not published |
| From (monthly) | £49 | £199 | $650 per user | £45 (£25 inside Sage 50) |
| Ledger integrations | Xero, QuickBooks Online and newer ledgers such as Rillet and Campfire (closed testing) on every plan; Sage Accounting and other ERPs on Custom | Xero, QuickBooks, Sage, NetSuite, Dynamics 365 Business Central | NetSuite, SAP, Sage Intacct, Business Central, Xero, QuickBooks Online | Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent |
| Chasing segmentation | Yes (per customer group) | Yes (4 schedules on Compact, unlimited above) | Yes (per workflow) | Yes (customer grouping and scheduling) |
| Late fee grain | Yes (per customer group) | Yes (one set of late-fee rules, across the account or for selected debtors) | None found | Optional, added to reminder emails |
| Statements | Yes (any schedule) | Yes (monthly, fixed day) | Yes (in the portal) | Yes |
| Payment plans | Yes (on Pro) | Yes | Yes | Not documented |
| Portal | Yes | Yes | Yes | Not documented |
| Credit checks | Yes: native checks from payment behaviour, plus Creditsafe via API on the Custom plan | Yes (Creditsafe) | Yes (AI scores, bureau integrations) | Yes (credit reports and limits) |
| Invoice finance | No | No | No | Yes (single and full) |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | Advanced Insights, Copilot drafts and an autonomous Agent; AI agent support from Business Plus; fully automated agent runs and AP portal features are billed separately by token use | None No AI feature found | |
| Rated (source, count) | 5.0 (84, Xero App Store) | 4.98 (374, Xero App Store) | 4.9 (117, G2) | 4.93 (92, Xero App Store) |
Read "Not published" as a vendor that puts no price in public and "None found" as no evidence in either direction. The prices are from-prices the vendors printed themselves.
The four tools in five checked facts
- All four print a monthly price: Satago from £45, Paidnice from £49 (US$69), Chaser from £199 and Kolleno from US$650.
- Each published price grows with something different: a flat tier (Satago), invoice volume (Paidnice), revenue band (Chaser) and users (Kolleno).
- Three of the four apply a late fee themselves: Paidnice (per customer group), Chaser (one set of late-fee rules) and Satago (optional, in reminder emails).
- All four connect to both Xero and QuickBooks Online.
- AI that handles collections work or customer replies: Paidnice and Kolleno. No AI in receivables: Satago.
We checked each tool's own pricing, integration and help pages. "None found" in the data means the vendor's pages do not show the feature.
1. Paidnice, best for rules per payer group
Best for: Charities with separate rules per payer group.
Paidnice is a reminder, late fee and interest tool for charities on Xero or QuickBooks Online, with a separate rule per payer group, from £49 (US$69) a month on Essentials.
What is Paidnice best for?
Choose Paidnice if you run a charity finance team on Xero or QuickBooks Online and want funders and members on a gentle cadence while commercial debtors get the full ladder, from one system.
- Fits
- UK charities, trusts and social enterprises on Xero or QuickBooks Online of any size up to $50m a year, or 50,000 invoices a year, with or without a credit controller
- Regions
- United Kingdom, Australia, New Zealand, United States, Canada, South Africa
- Entry cost
- £49 (US$69) a month on Essentials, covering 150 invoices, 600 emails and up to 2 team members; Pro from £74 (US$99) a month with unlimited users and no per-seat fee. Payment plans and sending from your own domain start on Pro. Check current pricing with the vendor
- Rated
- 5.0 from 84 Xero App Store reviews; 4.9 from 14 on Capterra
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero and QuickBooks Online on every plan, and newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo through the closed testing programme. Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive, Zapier. Sage Accounting, NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central on the Custom plan
- Statutory late fees
- Yes. A Bank of England base rate toggle applies the base rate plus your own percentage, using the correct base rate for each period an invoice spans, and policies sit under customer groups, so a funder group and a trading group run different rules at the same time
- Does best
- Several chasing and charging policies running at once, one per customer group, each posting its charge to the ledger
The customer group is what fits Paidnice to a charity ledger. Every payer type gets its own group, and the group carries its own reminder wording, its own schedule and its own charging policy, all running concurrently rather than one at a time.
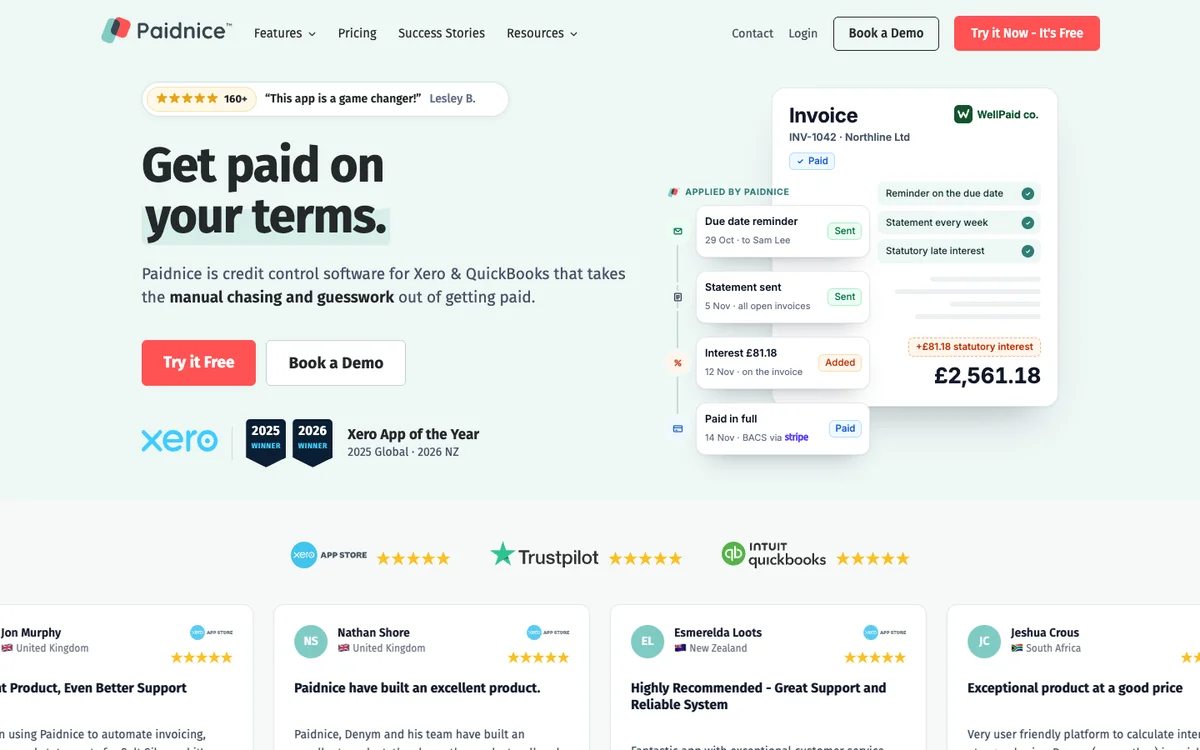
That maps directly onto a chasing policy a trustee board has approved, because the policy is written per payer type and the software is configured per payer type. Reminders go out over email and SMS, and from Pro they come from the charity’s own authenticated domain, so what a funder sees in the inbox is the finance office it already corresponds with.
Everything else is what a trading business gets. Statements run on whatever schedule you set, including consolidated parent accounts, which is the right shape for a funder holding several project codes under one relationship.
Payment plans start on Pro. Instalments run through Stripe or Pinch Payments with the schedule set against the invoice, which is how a phased settlement under a commissioning contract gets chased on its own dates.
Statement interest is recalculated as the statement leaves rather than at the last policy run, and the charge lands on the ledger as Draft or Approved, so a finance officer can hold it for approval before it becomes a receivable a funder can see.
Limitations with Paidnice. Xero and QuickBooks Online are on every plan, and newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice’s closed testing programme. Sage Accounting and other ERPs, including NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central, connect on the Custom plan as a build rather than a standard connector. A charity on Sage 50 or on a dedicated fund-accounting ledger is out of scope.
Restricted against unrestricted is not tracked here and is not supposed to be, so the SORP reporting stays in the charity ledger and this sits beside it. Essentials covers two team members, which a finance office running on part-time staff and volunteers can pass without meaning to.
Best Accounts Receivable Software for Non-Profits: 4 Tools Compared (1:40)
Video chapters and transcript
- 0:00 Short answer
- 0:21 What matters for a charity
- 0:47 Four tools, in alphabetical order
- 1:16 Published prices
Which accounts receivable software suits a UK non-profit? It depends on who is paying. A charity may need a gentle rule for funders and a firm one for trading customers.
Four tools are compared on that grain, on published price and on verified reviews. None of them was built for the charity sector, so each is judged on fit. A grant falls due when a condition is met, so it should stay out of automated chasing.
Trustees approve the chasing policy, and it must be written before the software is set up. Statutory interest applies to commissioned and trading invoices, never to grants. An invoice queued at a council usually needs its purchase order number, and a statement moves it faster than a reminder.
Keep the sent copy as audit evidence. Choose Chaser if a larger charity has a named credit controller and wants separate chase schedules and Creditsafe checks. Choose Kolleno if you are on NetSuite or Sage Intacct and need to allocate grant tranches and bulk public-sector remittances.
Choose Paidnice if funders and trading customers need different rules, with interest on the trading group only. Choose Satago if you are on Sage 50 or Xero, wait on local authority payers, and want invoice finance from the same provider. On price, Chaser starts at one hundred ninety-nine pounds a month.
Kolleno starts at six hundred fifty dollars per user. Paidnice starts at forty-nine pounds. Satago starts at twenty-five pounds inside Sage 50.
2. Chaser, best for a named credit controller
Best for: Charities with a named credit controller.
Chaser is a credit control tool with Creditsafe credit checks and separate chase schedules, from £199 a month for charities under £4m.
What is Chaser best for?
Choose Chaser if you run a charity or social enterprise with a named credit controller and want separate chase paths for funders, members and commercial clients, with bureau credit checks alongside them.
- Fits
- UK-centred organisations with a named credit controller; Compact is priced for turnover under £4m, Core from £4m and Complete runs to £100m
- Regions
- UK-registered, trading since 2014, sells worldwide
- Entry cost
- £199/mo on Compact for turnover under £4m, with 4 users, 4 schedules and 30 templates; Core £599/mo from £4m to under £10m with unlimited schedules; Complete £899/mo above that, to £100m.
- Rated
- 4.98 from 374 Xero App Store reviews; 4.3 from 71 on G2
- Awards
- Finalist, UK Small Business App Partner of the Year, Xero Awards 2023
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP, HubSpot, Gmail, Outlook
- Statutory late fees
- Yes. Four calculation types including a Bank of England base rate type, recalculated daily, but one set of late-fee rules, across the account or for selected debtors, not tied to schedules, and no documented way to run different rules per group. No fee is raised on payment-plan invoices, and Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero
- Does best
- Separate chase schedules per payer type, with Creditsafe credit checking and monitoring in the same tool as email, SMS and letters
- Customers
- Named on its website: Mindful Education, The Community Energy Scheme and Runway East. The Community Energy Scheme's case study reports £800,000 of old debt reclaimed.
Trading since 2014, Chaser sends out of whichever Gmail or Outlook mailbox the finance office already uses, and layers SMS, letters, a payer portal and partner collections on top of it.
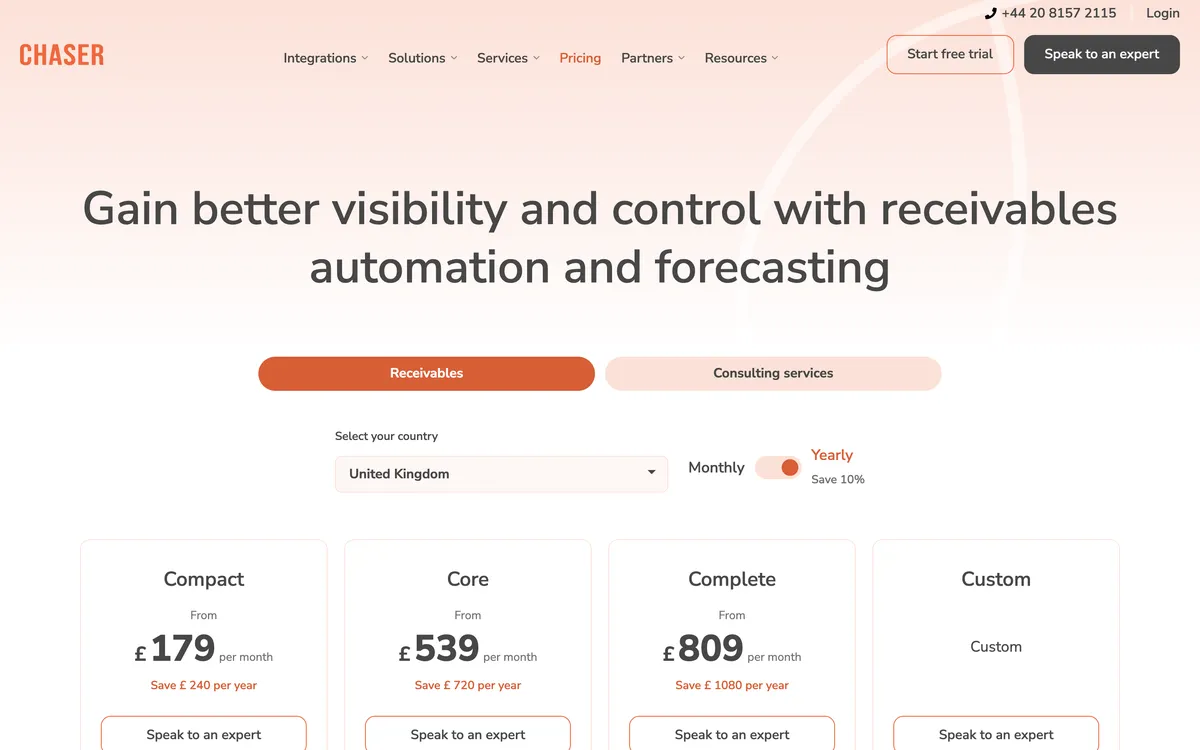
The number a charity should look at is the schedule count: four separate chase paths on the entry tier and unlimited above it.
The Creditsafe report built into it carries a score, a recommended limit, the customer’s payment score, credit event history, Companies House filing and director data, and continuous monitoring.
None of that is any use against a grant funder or a local authority, both of which are as good for the money as the sector gets. It is a commercial-debtor instrument, and it is the reason a charity with a real trading subsidiary ends up looking at Chaser at all.
Limitations with Chaser. It has one set of late-fee rules, across the account or for selected debtors, not tied to schedules, and no documented way to run different rules per group, so a charity can charge its trading subsidiary and leave its funders out, but every payer it charges gets the same rate.
No fee is raised on payment-plan invoices either, and Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero, which affects the accounts a phased commissioning settlement creates. Statements go monthly on a fixed day.
Compact holds the team to four users and four schedules, SMS, letters and calls draw metered credits, and £199 a month is a hard number to put in front of a small board. Credit checks are sold by credit on any plan and need Chaser billing, not Xero App Store billing.
3. Kolleno, best for NetSuite or Sage Intacct
Best for: Larger non-profits on NetSuite or Sage Intacct.
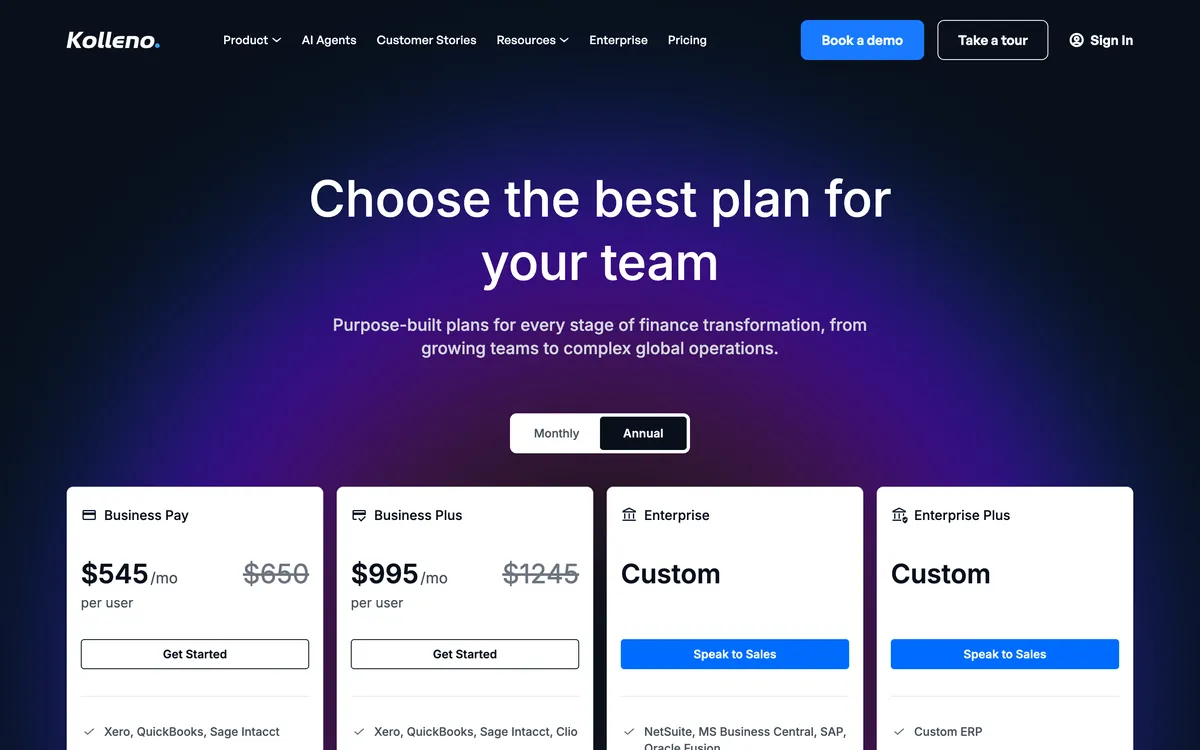
Kolleno is an order-to-cash platform for larger non-profits, from $650 per user a month on BusinessPay.
What is Kolleno best for?
Choose Kolleno if you run a larger non-profit or social enterprise on NetSuite or Sage Intacct and need remittance parsing and bank-file cash application as well as reminders.
- Fits
- Order-to-cash teams: BusinessPay for turnover under £1m, Business Plus £1m to £100m, Enterprise £100m to £1bn
- Regions
- London head office, founded 2020, selling internationally
- Entry cost
- $650 per user a month on BusinessPay, $545 on annual billing, minimum one user, for turnover under £1m; Business Plus $1,245 per user.
- Rated
- 4.9 from 117 G2 reviews; 5.0 from 18 Xero App Store reviews; 5.0 from 8 on Capterra
- Awards
- G2 Best Software Awards 2024
- Runs on
- NetSuite, SAP S/4HANA and Business One, Sage Intacct, Business Central, Workday, Oracle JD Edwards, Epicor, Infor, Odoo, Zuora, Xero, QuickBooks Online
- Statutory late fees
- None found. No feature page or help article documents a late fee or interest calculation
- Does best
- Cash application, with email remittance parsing, BAI2, NACHA and ISO 20022 bank files, match scoring and NetSuite multi-currency journal entries
- Customers
- Named on its website: Wise, Deel and Laundryheap. Laundryheap's case study reports 94% of payments collected on time.
Kolleno is an order-to-cash platform built around cash application: remittance emails parsed into suggested matches, SFTP bank connections, one-to-many matching, partials, credit-note offsets, foreign exchange and bank-fee handling.
Grant income arriving in tranches against several project codes, and a public-sector payment run clearing eleven invoices in one BACS line, are both hard to allocate and both routine at scale.
Chasing is assembled from trigger-based workflows with conditional branches and run-hour restrictions, so the funder path and the trading path are two workflows rather than two groups.
Its AI comes as insights, a copilot drafting messages for review, and an agent that works a collections policy unattended. Kolleno lists AI agent support from Business Plus, and fully automated agent runs and AP portal features are billed separately by token use. The unattended agent is a proposition a board will want to look at before it is enabled.
Limitations with Kolleno. $650 per user a month on BusinessPay, a tier for turnover under £1m that leaves out workflow automation, is outside what most UK charities will approve, and the next tier nearly doubles it, which is the whole conversation for anything under about £20m of income. Kolleno matches payments to invoices (auto-reconciliation) on Enterprise only, by quote, and BusinessPay does not include it. Xero and QuickBooks connect on BusinessPay and Business Plus; NetSuite and SAP start on Enterprise.
Nothing in its materials documents a fee or an interest calculation, so statutory interest on a trading invoice stays a manual job here. Kolleno includes 100 to 600 calls a plan. Its pricing page does not say which actions a workflow can hold. The complaints that recur in reviews are navigation and the depth of the reporting.
4. Satago, best for commissioned services
Best for: Sage 50 or Xero charities delivering commissioned services.
Satago is a credit reporting and chasing tool with optional invoice finance for Sage 50 or Xero charities, from £25 a month inside Sage 50.
What is Satago best for?
Choose Satago if you run a Sage 50 or Xero charity delivering commissioned services and want credit reports and invoice finance from the provider that runs your chasing.
- Fits
- UK organisations in the Sage and Xero ecosystem. No revenue band published
- Regions
- United Kingdom only
- Entry cost
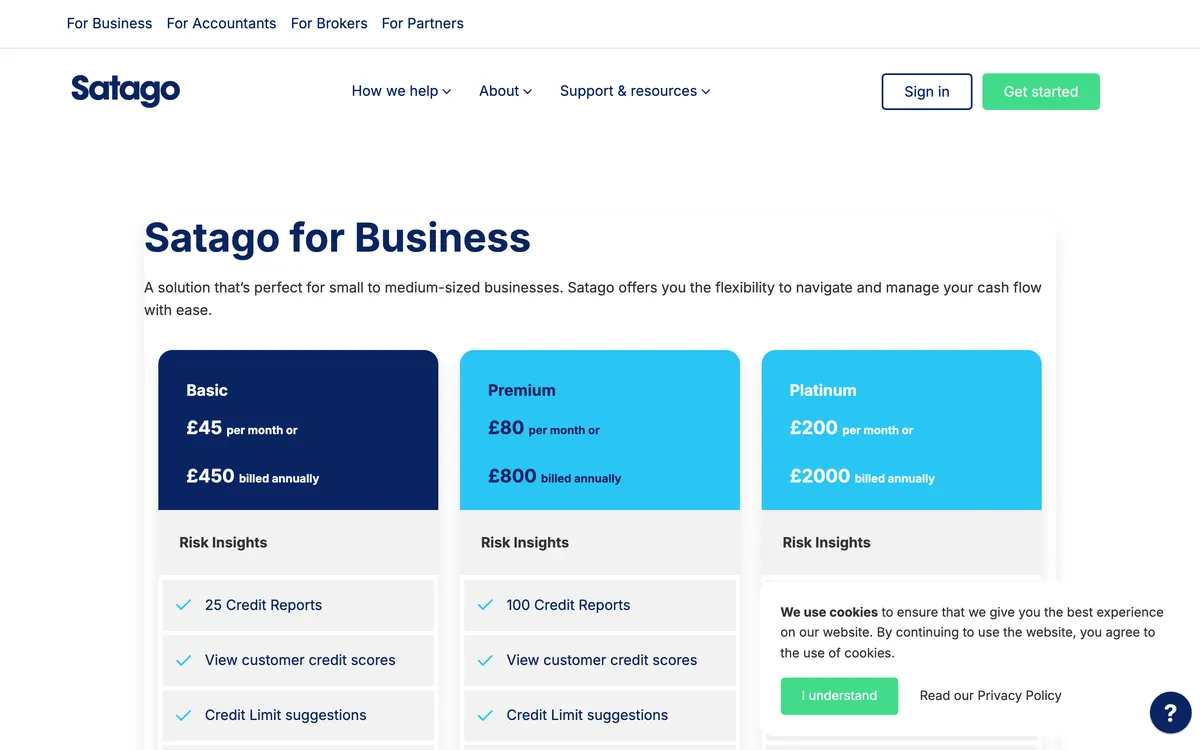
- £25/mo Standard and £45/mo Plus inside Sage 50, with Plus included on selected Sage 50 subscriptions; standalone £45/mo Basic, £80 Premium, £200 Platinum.
- Rated
- 4.93 from 92 Xero App Store reviews, UK listing
- Awards
- Not published
- Runs on
- Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent
- Statutory late fees
- Optional late fee added to reminder emails once overdue, calculated in line with statutory limits. The daily rate and fixed-sum band are not documented, and no ledger charge is documented
- Does best
- Credit reports, customer credit scores and suggested credit limits in the same subscription as the chasing, with invoice finance from the same provider
Satago is a UK hybrid, chasing and risk insights on one side, single and full invoice finance on the other. For a charity holding public-sector contracts the lending side is the part that matters, because the commissioner problem is a timing problem rather than a credit problem.
An authority sitting on a 30-day invoice for 90 days is going to pay. Advancing against that invoice solves the cash gap without a single escalation reaching the commissioning manager who signs the next contract.
The route in is usually Sage rather than the app. The embedded edition undercuts the standalone product at £25 a month on Standard, and Sage says the Plus tier comes with selected Sage 50 subscriptions without naming which ones.
What the bundle covers is reminders, statements, customer grouping and scheduling, which is enough to hold funders and trading customers apart on a Sage ledger and not enough to charge either of them anything.
Limitations with Satago. Basic holds you to 100 email reminders a month and does not list own-inbox sending; your own inbox starts at the £80 Premium tier. Satago adds an optional late fee to reminder emails without documenting a ledger charge, and it has 4.93 from 92 reviews on the Xero App Store.
The footprint stops at the United Kingdom.
How should a charity treat funders, commissioners and trading customers?
A charity ledger carries three kinds of income that arrive under three different legal arrangements, and each one wants a different answer to the question of what happens when the money is late.
A grant funder is a partner, and grant income is conditional rather than dated, so the concept of arrears does not apply. A commissioning body is a certain payer on an uncertain timetable, where the invoice is not at risk but escalating against it can cost the next contract.
A trading customer, whether that is room hire, a training course or the trading subsidiary invoicing a business, is an ordinary commercial debtor with no special claim on the charity at all.
A grant funder is not a debtor
A grant falls due when a condition is met, not when a date passes, so an unmet milestone sitting on the ledger looks exactly like an overdue invoice to software that only reads dates.
The failure mode is a reminder arriving at a funder about money the charity has not yet earned. Keep grant and milestone income out of the automated chasing altogether, or park it in a group with the chasing switched off, and check that decision every time a new award is coded.
The practical consequence is that one setting cannot serve all three. Every tool below can chase. What separates them is whether the chasing rule, the tone and the charge can be attached to the payer type rather than to the organisation.
One rule for the whole ledger
- Assumes every payer is a commercial debtor
- The same wording reaches a funder and a defaulter
- An unmet grant milestone reads as overdue
- The fee is on for everybody or off for everybody
A rule per payer type
- Funders and members in their own group
- A gentle cadence on one group, the full ladder on another
- Grant and milestone income out of the automated chasing
- Interest on trading customers only
What must a trustee-approved chasing policy contain?
In a charity the escalation ladder is a document, approved by trustees, defended at audit and quoted back at the finance officer the first time a funder complains, where in a trading business it is a setting somebody in finance chose.
An automated final notice reaching a long-standing funder is a reputational event, and a trustee will hear about it before the finance officer does.
Which payer types are chased automatically and which are handled by a named person. What the wording escalates to, and where it stops, for each of those types. Who authorises an exception, and how that exception is recorded. And whether interest is ever charged, against which payer, and who signs it off.
Then the software has to be able to hold it. A policy that gives funders and trading customers different terms needs more than one set of rules, because a tool with one set can only include or leave out a customer, not give each group terms of its own.
Two smaller things belong in the same document. Tone is auditable, so keep the sent copy: a dated record of what was sent to whom is the evidence that the approved wording was the wording used.
And the charge, if there is one, should be capable of being raised in draft and approved by a person before it reaches a payer, which is the difference between a policy with a control in it and a policy with a switch in it.
Can a charity charge statutory interest, and on which invoices?
The question resolves on the payer, not on the charity. Charitable status changes nothing about the entitlement, because the entitlement attaches to the supply rather than to the supplier.
Take the three payers in turn. A grant is not a commercial debt at all, so nothing under the Late Payment of Commercial Debts (Interest) Act 1998 applies to it, and no software setting changes that.
A commissioned service is a business-to-business supply, so the entitlement does apply, and a charity invoicing a local authority has exactly the same right to interest at 8% a year over the Bank of England base rate as any contractor.
The trading subsidiary invoicing a commercial customer is a company invoicing a company, with the fixed sum of £40, £70 or £100 by size of debt claimable on top. The base rate stood at 3.75% in mid-2026, making the total 11.75%, and it rose to 4% on 5 November 2026, so read the current one on GOV.UK before it goes on an invoice.
Being entitled and being willing are separate questions, and the second one is where most charities stop. Invoicing a commissioner for interest is legally clean and commercially expensive, because the same relationship is up for renewal.
So the useful configuration is interest live on the trading group and switched off everywhere else, which is a charge a finance officer can also waive in writing in return for settlement this week.
What is settled law, and what is still a bill
- Statutory interest
- Available on a commissioned or trading invoice, never on a grant. The rate runs 8% over the Bank of England base rate, which put the total at 11.75% in mid-2026 and moves whenever the base rate does, so read it again before the invoice goes out. GOV.UK
- Fixed compensation
- A flat sum per invoice on top of the interest, banded by the size of the debt at £40, £70 and £100, and claimable by a charity on the same basis as by anyone else. GOV.UK
- Mandatory interest
- A bill rather than an entitlement. If the Commercial Payments Bill passes as drafted, statutory interest stops being a default that a contract can waive and becomes compulsory, which would remove a clause some commissioners currently insert. Check where it has reached before anything is built on it.
Interest on the subsidiary, none on the funder
Paidnice and Chaser both document a base rate calculation, so the arithmetic is not what separates them. The question a charity has to answer is whether the software can hold two different answers for two different payers at the same moment.
Only in part. Chaser can charge selected debtors and leave others out, but it has one set of late-fee rules, not tied to schedules, and no documented way to run different rules per group, so every payer it charges is under the same rules.
Paidnice can, because policies hang under customer groups: interest runs on the trading group at base rate plus your percentage, calculated per period so an invoice spanning two base rates is charged correctly, while the funder group carries none, and both states exist on the same ledger at the same time.
The charge is raised as Draft or Approved, which is the control a board will ask for.
Kolleno computes nothing here and Satago only adds an optional late fee to its reminder emails, so on both of those the entitlement stays a spreadsheet and a manual credit note.
A £8,000 commissioned-services invoice, 60 days past its 30-day terms, at 11.75%: £154.52 of interest, £70 of fixed compensation, £224.52 claimable.
The interest is the balance at the rate, apportioned across the days it ran late; the fixed sum steps at £40 below £1,000, £70 up to £9,999.99 and £100 from £10,000.
How should a charity chase a council that has its invoice?
The invoice is undisputed, it is not at risk and the payer has the money. It is queued behind a portal, a purchase order number and an approval that has not happened yet.
Which is why the standard escalation ladder does nothing to it.
A final notice reaches them again and is forwarded, with a comment, to the commissioning manager who decides on the next contract, which is the one outcome the charity was trying to avoid.
What moves a queued invoice is administrative rather than persuasive. The purchase order number has to be on the invoice, in the field the portal reads, because a mismatch there is the single most common reason an invoice is parked.
The statement, rather than the reminder, is the document an authority acts on, because it shows the whole account rather than one line. Many authorities publish their own prompt-payment performance, which is a fact that can be quoted politely.
None of the four tools on this page models any of that. There is no purchase order validation, no portal read, no authority-specific route.
What they can do is keep a dated evidence trail, which is worth more here than pressure is: a record of when the invoice was sent, when the statement went, what was said and to whom, ready for the moment somebody at the authority asks for proof.
The one collections mechanic that does fit a commissioner is a phased settlement. Where an authority agrees to clear a backlog across several months, Chaser will split the invoice weekly through to yearly but keeps chasing the original due date rather than the instalment dates, and its own documentation advises chasing the instalments manually.
Kolleno splits weekly, monthly or bi-monthly with automations linked to the plan, though uneven totals are divided manually. No instalment function is documented for Satago at all.
What is accounts receivable software for non-profits, and what is it not?
A receivables tool chases what has been invoiced, and fund accounting tracks restricted against unrestricted income on the same ledger. Chasing what has been invoiced, charging for the wait, issuing the statement and taking the payment is one job.
Tracking restricted against unrestricted income and reporting it under the Charities SORP is the other, and nothing on this page does the second one.
The Charity Commission register for England and Wales runs past 160,000 organisations, and the smaller ones keep their books on the same ledgers a trading business uses. There is no separate software category waiting for them, which is why this shortlist is a general one and why the whole comparison turns on the payer rather than on the product.
- Reminders with wording per payer type: scheduled email and SMS before and after the due date, worded the way the approved policy says for that group.
- A live read of the ledger: so the chase stops the day the money lands and no funder is ever chased for a grant already banked.
- Segmentation that survives an audit: groups or schedules that keep the commissioned-services account on one ladder and the grant funder off it entirely.
- Statements on a schedule: the account summary, which is more often than not the only document a slow public-sector payer responds to.
- A page the payer can serve themselves from: view the invoice, pull the statement, pay, or start a schedule, without a message reaching anybody.
Restricted funds never leave the charity ledger
Income recognition tightens under the 2026 Charities SORP, and no receivables tool in this comparison tracks restricted against unrestricted at all. That reporting stays in the ledger or the fund-accounting system that already produces it. What the receivables tool owns is narrower and worth being precise about: the chasing, the charge and the statement.
What can a small charity approve, by income band?
A small charity should choose by what its board will sign, not by what the organisation could afford.
- Under £500k. The ledger's own reminders often are enough, and if they are not, Satago inside Sage 50 at £25 is a step past them that is easy to put in a paper. Paidnice at £49 (US$69) if funders and trading customers need different rules from the first month.
- £500k to £4m. Usually the band where a trading arm becomes material. Chaser at £199 if there is a named credit controller and the credit checking is genuinely being used, or Paidnice for per-group policies on a flat price.
- £4m to £20m. Chaser or Paidnice, decided on one question: whether the approved policy needs different late-fee rules for different payer groups. If it does, Chaser has no documented way to deliver it. If it does not, Chaser from £599 on Core buys monitoring and a longer ledger list.
- Above £20m. Kolleno when allocating grant tranches and bulk public-sector remittances is the real bottleneck rather than the chasing, or Chaser's Complete tier to keep everything on one system.
Which charity ledgers do these tools connect to?
A charity on a dedicated fund-accounting system has no option on this page, because none of the four connects to one.
- Xero. All four connect. A Xero organisation already using tracking categories for funds keeps that reporting exactly where it is and bolts the chasing on above it.
- QuickBooks Online. All four again, with class tracking doing the same job Xero categories do.
- Sage 50 and Sage 200. A large slice of the sector sits here, and the list shortens sharply: Satago embedded at £25 a month, and Chaser. Paidnice does not serve Sage 50 or Sage 200, which removes the per-group charging option from any charity on it.
- NetSuite and Sage Intacct. Kolleno, and Chaser on NetSuite. Paidnice reaches NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central on its Custom plan only, as a build rather than a connector, so budget it as a project.
What does this cost against a restricted-funds budget?
The awkward part of this purchase is that it is core cost. Chasing income is support, not delivery, so it is paid for out of unrestricted funds or out of a thin allocation, and every pound is visible.
Published UK entry prices: Chaser £199, Kolleno $650 per user, Paidnice £49 (US$69) and Satago £25 inside Sage 50. Not one of the four publishes a charity rate.
The metric matters more here than in any commercial sector, because charity income and charity capacity move independently. Chaser prices on turnover, so a single large restricted grant can push an organisation into a higher tier while adding nothing at all to the unrestricted budget the subscription is paid from.
Kolleno prices per user, so a finance office of three multiplies the bill by three before anything is chased.
Paidnice prices on invoice volume, flat, with no per-seat charge, which suits a finance function staffed by part-timers and volunteers who each need a login.
Which accounts receivable software for non-profits fits your use case?
| Use case | Start with | Why | Watch out |
|---|---|---|---|
| Charity on Xero or QuickBooks Online with funders, members and trading customers on different rules | Paidnice | Wording, schedule and charging rule per customer group, with interest on the trading group only | Xero, QuickBooks Online and newer ledgers (closed testing) on every plan, Sage Accounting and other ERPs on Custom; no Sage 50 or Sage 200 |
| Reminders and statements only, no interest | Paidnice | A gentle cadence for funders and statements on any schedule from £49 (US$69) a month; charging is optional | Essentials covers two team members |
| Named credit controller and a real trading subsidiary | Chaser | Four chase schedules on the entry tier and Creditsafe checks on commercial debtors | One set of late-fee rules, from £199 a month |
| Charity on Sage 50 | Satago | Reminders, statements and customer grouping from £25 a month inside Sage 50 | Late fee sits in reminder emails, and UK only |
| Cash timing on public-sector contracts | Satago | Invoice finance against a commissioned-services invoice, with no escalation to the commissioner | Borrowing, so a board decision |
| Larger non-profit allocating grant tranches and bulk remittances | Kolleno | Remittance parsing and bank-file cash application | $650 per user a month, and no interest calculation documented |
What do charity finance officers ask?
Is there accounts receivable software built for charities?
No, and it is worth stopping the search early. Nothing mainstream in receivables or credit control is built for the sector. What works is a general tool that segments payers properly, so funders and members can be treated differently from trading customers, with restricted and unrestricted tracking left in a charity-aware ledger where it belongs.
How should a charity chase a slow-paying council?
A charity should chase a slow-paying council administratively rather than firmly. Check the purchase order reference is on the invoice in the field the portal reads, send the statement rather than another reminder, and route the query to the commissioning manager instead of up an escalation ladder to them.
Where the problem is cash timing rather than the relationship, advancing against the invoice is what Satago sells alongside its software, and that is a board decision.
Can a charity charge statutory interest on a late invoice?
Yes, and charitable status is irrelevant to the answer. The entitlement attaches to the supply: a commissioned service, a room hire or a trading subsidiary sale is a business-to-business invoice and carries interest at 8% a year over the Bank of England base rate, 11.75% at the mid-2026 rate of 3.75%, plus £40, £70 or £100 by size of debt.
A grant is not a commercial debt and carries none of it, and whether to raise it on a commissioner is a trustee question rather than a legal one.
Which tools let a charity chase funders and trading customers differently?
All four do, at different grains: Chaser gives four separate chase schedules on the entry tier and unlimited above it, but one set of late-fee rules, not tied to schedules, sits behind all of them.
Kolleno splits payers by workflow, which is administered rather than labelled, and Paidnice changes wording, schedule and charging rule together because all three hang off the same customer group. Satago documents grouping and scheduling and publishes no detail on the rules underneath.
Do we still need this if Xero already sends reminders?
If every payer can be treated the same way, the built-in reminder is genuinely enough and nothing on this page is worth the money.
The ceiling arrives the moment an approved policy says a funder and a trading customer are handled differently, because the ledger sends one schedule with one wording to everybody, applies no interest, produces no automatic statement and reports nothing about whether any of it brought the money in.
What does receivables software cost a non-profit?
Chaser is £199 under £4m of turnover, Kolleno is $650 per user and Paidnice is £49 (US$69) on Essentials. Satago runs £25 embedded in Sage 50 and £45 standalone. None of them publishes a charity rate.
To compare the same tools for any business type, read the best credit control software guide, which sets out six tools by size, ledger and price.
Related reading for charity finance teams
Buyer's guide
Best credit control software UK
Six credit control systems compared on statutory interest and reviews.
Getting paid
How to chase overdue invoices
The sequence, the channels, and when to escalate.
Templates
Overdue invoice email templates
Five copy-paste emails from a friendly nudge to a final notice.
UK law
Late payment fees in the UK
The complete guide to the law, the rate and what is changing.
Sources
13 sources, checked by Julie Turnbridge on November 6, 2026
- Xero Small Business Insights xero.com/uk/resources/small-business-insights
- Xero App Store apps.xero.com/uk/app/paidnice
- Capterra capterra.co.uk/software/254868/paidnice
- Xero App Store apps.xero.com/uk/app/chaser
- G2 g2.com/products/chaser/reviews
- G2 g2.com/products/kolleno/reviews
- Xero App Store apps.xero.com/uk/app/kolleno
- Capterra capterra.co.uk/software/227932/Kolleno
- Late Payment of Commercial Debts (Interest) Act 1998 legislation.gov.uk/ukpga/1998/20/contents
- Bank of England base rate bankofengland.co.uk/monetary-policy/the-interest-rate-ban...
- GOV.UK gov.uk/late-commercial-payments-interest-debt-recovery/ch...
- GOV.UK gov.uk/late-commercial-payments-interest-debt-recovery/cl...
- Charity Commission register-of-charities.charitycommission.gov.uk/en/sector-...