The best credit control software in 2026 for a Xero or QuickBooks Online business of any size up to $50m a year is Paidnice, which applies late fees and interest per customer group. Large B2B credit teams buy credit management suites instead. This page compares credit control software for businesses collecting on credit they have already given.
- Best for credit decisioning and credit applications: Bectran and Onguard, enterprise platforms for a B2B credit team that approves applications, sets credit limits and blocks orders when risk changes.
- Best for bureau risk data: Creditsafe, Experian and Dun & Bradstreet, for a team that wants credit scores and reports to feed its own credit process.
- Best for credit inside an order-to-cash suite: HighRadius and Esker, for a large B2B team that runs credit management inside a wider order-to-cash platform on its ERP.
- Best for credit control after the sale: Paidnice, Chaser, CreditorWatch Collect, ezyCollect, Kolleno and Satago, for a business that chases invoices on its own ledger. The table below gives each one a fit line.
Credit management software automates the credit workflow, and a credit data provider such as Creditsafe supplies the risk data that workflow uses.
| Tool | Best for | From (monthly) | Rated (count, source) |
|---|---|---|---|
| Paidnice | Paidnice fits a Xero or QuickBooks Online business that wants a late fee and interest charge per customer group, posted to the ledger | US$69 | 5.0 (83, Xero App Store) |
| Chaser | Chaser fits a team that wants Creditsafe credit checks and multi-channel chasing in the same tool, up to £4m on the entry tier | US$259 (£199 in the UK) | 4.98 (374, Xero App Store) |
| CreditorWatch Collect | CreditorWatch Collect fits an Australian business that wants part of the chasing done by people, pricing on request | Last reported A$89; now hidden, request a quote | 4.9 (91, Xero App Store AU) |
| ezyCollect | ezyCollect fits an Australian trade or wholesale seller that wants credit screening with its collections | A$275 (last published; now hidden, request a quote) | 4.9 (35, Xero App Store AU) |
| Kolleno | Kolleno fits an order-to-cash team on NetSuite or SAP | $650 per user | 4.9 (117, G2) |
| Satago | Satago fits a Sage 50 or Xero team that wants credit reports and invoice finance with its chasing | £25 inside Sage 50 | 4.93 (92, Xero App Store) |
Where a business trades changes how long it waits: a New York small business waits 38.7 days to be paid against 24.1 days in California, on Xero Small Business Insights data for June 2026. The US average sits at 29.1 days, up from 27.5 a year earlier, settling 8.3 days past due.
Credit management software vs credit control software: what is the difference?
Credit management software decides whether a customer gets credit, and credit control software collects on the credit you have already given.
- Credit management: credit applications, a credit check against bureau data from Creditsafe, Experian or Dun & Bradstreet, a credit limit per account, and blocked orders when risk changes. A credit team runs it, often inside an ERP order-to-cash process.
- Credit control: reminders, statements, late fees and interest, payment plans and a customer payment portal, synced to Xero, QuickBooks Online, Sage or another ledger.
- Enterprise credit management: HighRadius, Bectran, Esker and Onguard sell credit decisioning to large B2B finance teams. This list does not review them.
- Both halves in one tool: Chaser, CreditorWatch Collect, ezyCollect, Kolleno and Satago add credit data to the chasing on their standard plans. Paidnice runs native credit checks from each customer's payment behavior, and Creditsafe bureau checks through the API on the Custom plan.
Which credit control software fits your annual revenue?
Credit control software fits by annual revenue first, because most vendors gate their plans by turnover. The bands below use each vendor's own published gate, printed in the vendor's currency, so a tool appears in every band its plans cover.
| Annual revenue | Tools whose published gate covers it |
|---|---|
| Up to $1m | Chaser (Compact, to £4m turnover), Kolleno (BusinessPay, under £1m), Paidnice (any size up to $50m a year) |
| $1m to $10m | Chaser (Compact to £4m, Core to £10m), Kolleno (Business Plus, from £1m), Paidnice |
| $10m to $50m | Chaser (Complete, above £10m), Kolleno (Business Plus, to £100m), Paidnice (up to $50m a year, or 50,000 invoices a year) |
| Above $50m | Chaser (Complete, to £100m on its pricing page), Kolleno (Business Plus to £100m, then Enterprise), or the enterprise credit management platforms above |
| No revenue gate published | CreditorWatch Collect (quoted after a trial), ezyCollect (banded by active debtors), Satago (metered by credit reports and reminders) |
Credit Hound, a Sage-channel collections add-on from Draycir, costs US$25 to US$454 a month for the first user and rates 5.0 from 11 Sage UK Marketplace reviews. This page does not review it.
What credit control software is (and what it is not)
Credit control software chases and enforces the invoices you have already issued: reminder sequences, statements, late fees and interest, payment plans, a customer payment portal and a handoff to a collection partner. Some tools add a credit check before terms go out.
It sits on top of the ledger. It reads invoices and payments from Xero, QuickBooks Online, Sage or another ledger, and posts any fee back to the customer's account.
- It is not the ledger: invoices are still raised in Xero, QuickBooks Online or Sage.
- It is not a debt collection agency, which takes over once you decide the debt is not coming in and keeps a percentage of what it recovers.
- It is not invoice finance, although Satago sells both from one provider.
Xero files these apps under Debtor Management, FreeAgent calls it Credit Control, and enterprise vendors sell the same work as Credit Management or order-to-cash.
How much is a commercial late fee worth?
Outside the United Kingdom a late fee is contractual rather than statutory: a percentage of the overdue balance per month, commonly 1 to 2 percent, prorated over the days the invoice ran late.
The UK case is different and is covered on the UK credit control comparison.
On $10,000 overdue for 45 days at 1.5% a month, the late fee is $225.00, an annual equivalent of 18%, so $10,225.00 is due in total.
The fee is the overdue amount multiplied by the monthly rate, prorated over a 30-day month for the days it was late. Rate ceilings are set by local law and by your contract, so confirm both before you charge one.
Doing that arithmetic for every overdue invoice, every month, and posting the result to the customer's ledger is the work Paidnice and Chaser take over.
How this list was put together
This list helps a business on Xero, QuickBooks Online or Sage choose credit control software that chases and enforces issued invoices.
| What we checked | Where the evidence came from |
|---|---|
| Revenue fit | Each vendor's pricing page and plan limits |
| Ledger integrations | Vendor integration pages |
| Late fee grain | Vendor help pages on fees and interest |
| Statements, payment plans and a portal | Vendor feature pages |
| Credit checks | Vendor product pages |
| Published from-price and rating | The vendor's pricing page, the last reported price where it is now hidden, and the Xero App Store or G2 rating with its review count |
How do these credit control tools compare?
The comparison table shows which credit control tools apply a late fee, carry credit data, publish a price and hold a verified rating. Paidnice and Chaser apply a late fee themselves. Paidnice runs native credit checks from each customer's payment behavior, and Creditsafe bureau checks through the API on the Custom plan.
 |
 |
 |
 |
 |
 |
|
|---|---|---|---|---|---|---|
| Revenue fit | Any size up to $50m a year, or 50,000 invoices a year | £4m and under on the entry tier, tiers to £100m on its pricing page | Not published (banded by debtor count) | Not published (banded by active debtors) | Under £1m on BusinessPay, tiers to £1bn and above | Not published |
| From (monthly) | US$69 | US$259 (£199 in the UK) | Not published | A$275 (AUD only; annual billing, plus setup from A$900) (last published; now hidden, request a quote) | $650 per user | £25 inside Sage 50 (GBP only) |
| Ledger integrations | Xero, QuickBooks Online | Xero, QuickBooks, Sage, NetSuite, Dynamics 365 | Xero, MYOB, QuickBooks Online | Xero, MYOB, QuickBooks Online, NetSuite, Sage 300, Sage Intacct, SAP Business One | NetSuite, SAP, Sage Intacct, Dynamics 365, Xero, QuickBooks Online | Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent |
| Late fee grain | Yes (per customer group) | Yes (one global rule) | None found | None found | None found | Not documented |
| Statements | Yes (any schedule) | Yes (monthly, fixed day) | Yes | Yes (monthly) | Yes (in the portal) | Yes |
| Payment plans | Yes | Yes | Yes (recurring debits in the portal) | Yes | Yes | Not documented |
| Portal | Yes | Yes | Yes | Yes | Yes | Not documented |
| Credit checks | Yes: native checks from payment behavior, plus Creditsafe via API on the Custom plan | Yes (Creditsafe) | Yes (parent-side payment scores) | Yes (Experian data) | Yes (AI scores, bureau integrations) | Yes (credit reports, scores and suggested limits) |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | None No AI features | None No AI feature found (risk ranking is rule-based) | Basic an AI email template generator as a paid add-on; Aimie is in early access | Advanced Insights, Copilot drafts and an autonomous Agent, in every tier | None No AI feature found |
| Rated (source, count) | 5.0 (83, Xero App Store) | 4.98 (374, Xero App Store) | 4.9 (91, Xero App Store AU) | 4.9 (35, Xero App Store AU) | 4.9 (117, G2) | 4.93 (92, Xero App Store) |
"Not documented" means the vendor does not document the capability. "Not published" means the vendor does not print a price. "None found" means no evidence either way. Prices are the vendor's published from-price. Check current pricing with the vendor.
Prices are in US dollars wherever the vendor publishes a US dollar price. Satago publishes only pounds sterling and ezyCollect only Australian dollars, so those two stay in the vendor's currency. Nothing is converted.
1. Paidnice, best for late fees and interest per customer group
Best for businesses up to $50m a year on Xero or QuickBooks Online that want late fees and interest applied per customer group, from US$69 a month on Essentials.
What is it best for?
Choose Paidnice if you run Xero or QuickBooks Online and want the fee and the interest applied per customer group and posted to the ledger, rather than another reminder.
- Fits
- Businesses on Xero or QuickBooks Online of any size, up to $50m a year or 50,000 invoices a year, with or without a credit controller.
- Regions
- United States, United Kingdom, Australia, New Zealand, Canada, South Africa.
- Entry cost
- US$69/mo on Essentials, covering 150 invoices, 600 emails and up to 2 team members; Pro from US$99/mo with unlimited users and no per-seat fee.
- Rated
- 5.0 from 83 Xero App Store reviews on the UK listing; 4.9 from 14 on Capterra.
- Awards
- Winner, New Zealand Small Business App of the Year, Xero Global App Awards 2026; 2025 Xero Global Small Business App of the Year.
- Runs on
- Xero, QuickBooks Online, Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive, Zapier. NetSuite, Sage Intacct, MYOB, Dynamics 365 Business Central and Creditsafe bureau checks on the Custom plan only.
- Late fees and interest
- Yes. Paidnice runs two charge types on the same customer group, an invoice late fee and a statement interest charge, both raised on the ledger as Draft or Approved. A Paidnice Bank of England base rate toggle indexes the rate for UK customers, and policies sit under customer groups, so different groups run different rules at once.
- Does best
- Ending the chase in a posted charge, so being late costs the customer something inside their own payables system.
Paidnice is the enforcement layer on top of Xero and QuickBooks Online: reminder sequences per customer group, statements on the schedule you set including consolidated parent accounts, payment plans on Pro and up, prompt payment discounts and a customer payment portal.
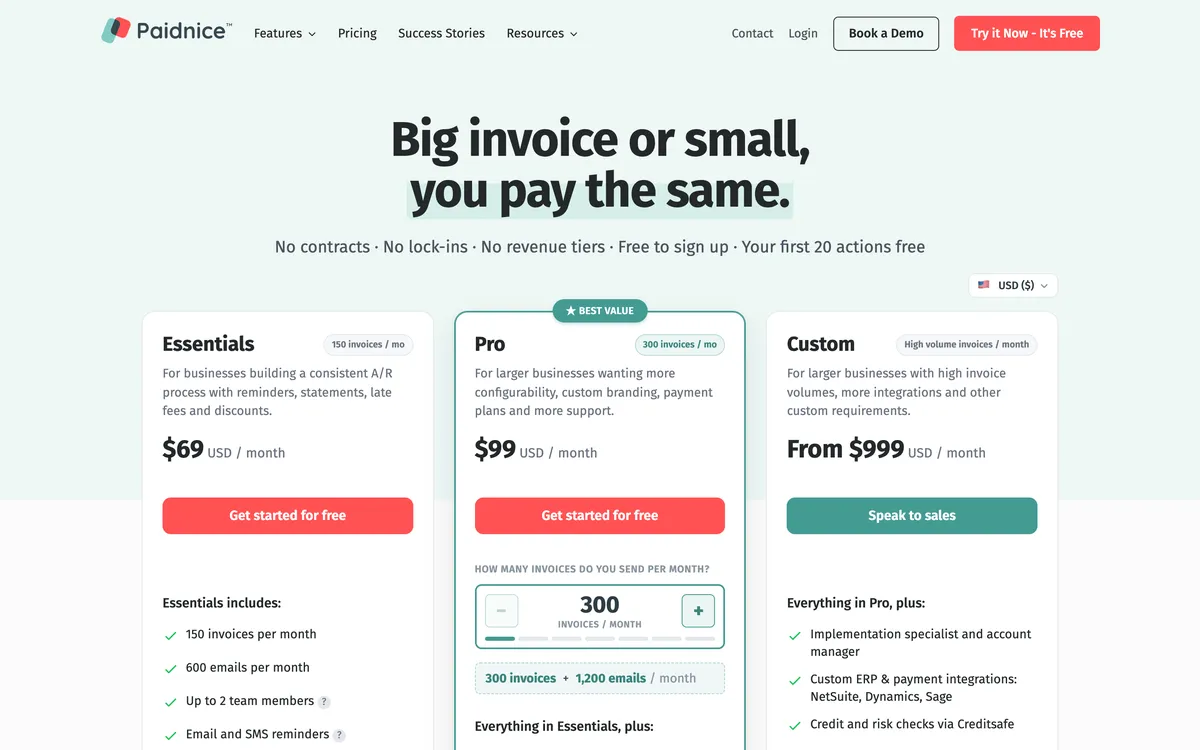
Email and SMS reminders run on every plan, and on Pro they send from the business's own authenticated domain.
Statement interest recalculates at the moment the statement sends rather than at the last policy run, so the figure the customer opens is accurate that morning.
Limitations with Paidnice. Native to Xero and QuickBooks Online only. NetSuite, Sage Intacct, MYOB and Dynamics 365 Business Central sit on the Custom plan as a build rather than a standard connector, and some payment features differ between the two ledgers. The entry tier covers two team members.
Paidnice's review base is smaller than Chaser’s, 83 reviews against 374.
Best suited for: A Xero or QuickBooks Online business of any size up to $50m a year that wants late fees and interest applied per customer group. Ledgers such as NetSuite or MYOB sit on the Custom plan only, from US$999 a month.
Best Credit Control Software: Which Tool Fits Which Business (1:38)
2. Chaser, best for teams with a named credit controller
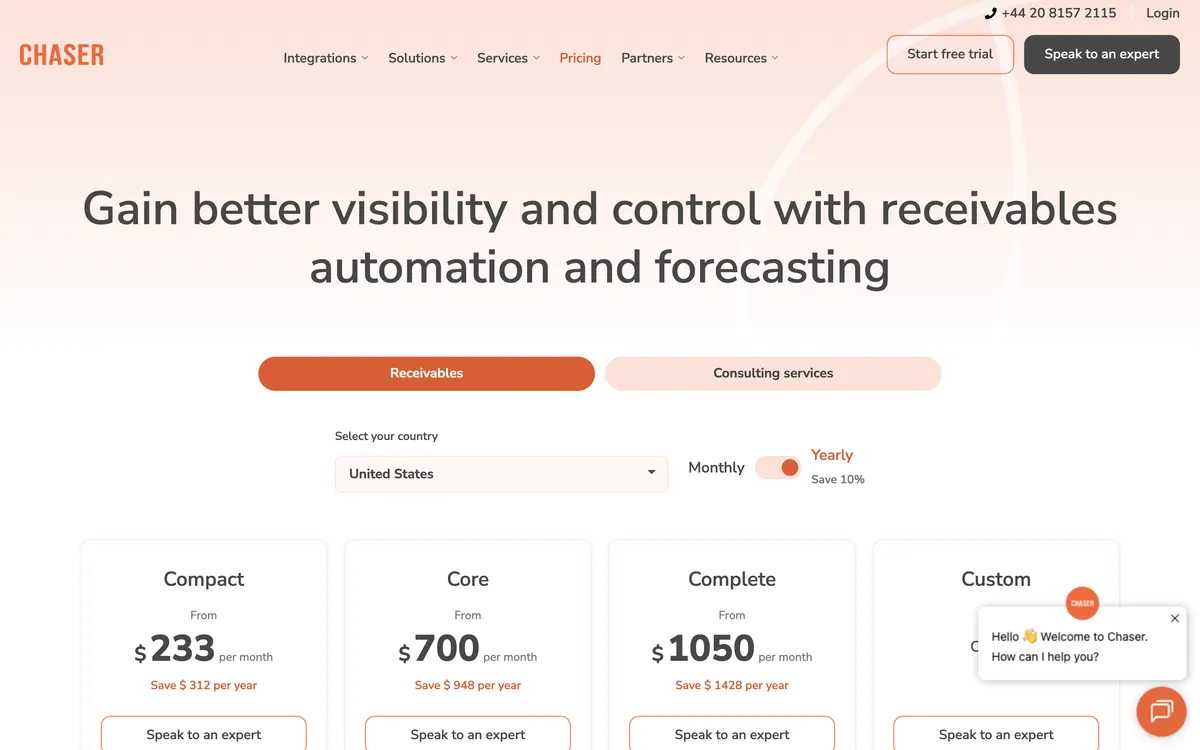
Chaser is a credit control tool with Creditsafe credit checks and email, SMS, letter and call chasing, from US$259 a month (£199 in the UK) for turnover up to £4m.
What is it best for?
Choose Chaser if you have a named credit controller and want Creditsafe credit checks, email, SMS and letters running from one system.
- Fits
- Businesses with a named credit controller; Chaser's entry tier is priced for £4m turnover and under, and the tiers run to £100m.
- Regions
- UK-registered, trading since 2014, sells worldwide.
- Entry cost
- US$259/mo on Compact (£199 in the UK) for turnover to £4m with 4 users; Core £599/mo to £10m; Complete £899/mo above that. Chaser Care, the managed service bundled with the software, starts at £899/mo on Compact.
- Rated
- 4.98 from 374 Xero App Store reviews; 4.5 from 68 on G2; 4.9 from 45 on Capterra, mostly dated 2020 to 2022.
- Awards
- Xero App Partner of the Year 2023.
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Central, NetSuite, Dynamics 365, AccountsIQ, SAP, HubSpot, Gmail, Outlook.
- Late fees and interest
- Yes. Chaser offers four calculation types, fixed through daily percentage and a Bank of England base rate type, recalculated daily, but one global rule only, which cannot vary by schedule or customer group, and no fee is raised on payment-plan or partially paid invoices.
- Does best
- Creditsafe credit checking and monitoring in the same tool as email, SMS and letter chasing.
- Customers
- Named on its website: Pact Coffee, Huttie and TaxAssist. Huttie's case study reports £15,000 of old debt recovered.
Chaser has been in the market since 2014 and sends reminders from the team's own Gmail or Outlook mailbox, adding SMS, letters, a payer portal and integrated collections through a partner. Channels are credit-metered, so letters, SMS and calls are billed on top of the plan.
Limitations with Chaser. One global fee rule works for a business selling into one market and breaks once a second market has different terms, because the rate, the trigger and the wording cannot vary by customer group. No fee is raised on part-paid or payment-plan invoices.
Statements go monthly only, on a fixed day, and Compact caps the team at four users.
Best suited for: A team with a named credit controller that wants Creditsafe credit checks with email, SMS and letter chasing in one tool. Its one global fee rule cannot vary by customer group, and statements go monthly on a fixed day only.
3. CreditorWatch Collect, best for Australian owners wanting a calling queue
CreditorWatch Collect is a reminder and calling workflow with an optional paid human calling add-on (Call Assist) for Australian businesses, with no published software price after a 14-day trial.
What is it best for?
Choose CreditorWatch Collect if you run an Australian owner-run business and want a calling queue, or actual people making the calls, on top of automated reminders.
- Fits
- Australian small and mid-sized businesses. CreditorWatch Collect publishes no revenue band; its historic tiers were banded by debtor count.
- Regions
- Australia and New Zealand, with escalation partners in the United Kingdom and United States. CreditorWatch Collect was founded in Christchurch in 2012 as Debtor Daddy, acquired by CreditorWatch in October 2022 and rebranded in March 2023.
- Entry cost
- Not published. The CreditorWatch Collect route is a 14-day trial for up to 50 debtors, then a quote from an account manager. Last reported tiers ran A$89 to A$849 a month by debtor count; now hidden, request a quote. Call Assist human calling is a paid add-on at A$195, A$495 or A$795 a month.
- Rated
- 4.9 from 91 Xero App Store AU reviews, many of them written before the rebrand; 4.5 from 13 on Capterra
- Awards
- None found.
- Runs on
- Xero on a 24-hour sync with a manual trigger, MYOB, QuickBooks Online, Zapier.
- Late fees and interest
- None found. Nothing on the CreditorWatch Collect features page, help center or FAQ documents a late fee or interest charge.
- Does best
- The human layer: a Call Console that builds the day's calling queue automatically, and Call Assist, a paid add-on (A$195 to A$795 a month) in which trained local AR specialists make the calls on your rules and log every outcome.
CreditorWatch Collect escalation is a one-click handoff to debt collection and legal partners across Australia, New Zealand, the United Kingdom and the United States, commission-only on recovery, for undisputed debts over $500 and under two years old.
Limitations with CreditorWatch Collect. No late fee or interest, and no published software price at any tier. The Xero connection syncs on a 24-hour cycle rather than in real time.
Much of the 91-review base predates the 2023 rebrand, so the score describes an older product. There is no public API beyond Zapier.
Best suited for: An Australian owner-run business that wants a calling queue, or paid human callers, on top of automated reminders. It has no late fee or interest, and no published software price at any tier.
4. ezyCollect, best for Australian wholesalers screening customers before terms
ezyCollect is a collections platform with Experian credit screening for Australian trade and wholesale sellers, from a last-published A$275 a month on annual billing plus a one-off setup fee from A$900.
What is it best for?
Choose ezyCollect if you run an Australian wholesale or distribution business on MYOB, Xero or SAP Business One and want customers screened before terms go out and chased consistently afterwards.
- Fits
- Australian and New Zealand trade, wholesale and distribution businesses. ezyCollect publishes no revenue band; its pricing is banded by the number of active debtors.
- Regions
- Australia and New Zealand primarily, with a United States payment option. ezyCollect was acquired by Sidetrade in October 2025 and relaunched in July 2026.
- Entry cost
- A$275/mo on ezyStart for up to 200 debtors, 3 users and 1 workflow on annual billing, plus a one-off setup fee from A$900. ezyCollect month-to-month billing is about 20 percent higher. ezyGrow A$950/mo, ezyScale A$2,350/mo. Last published; ezyCollect now hides its pricing, request a quote.
- Rated
- 4.9 from 35 Xero App Store AU reviews; 4.7 from 25 on G2; 4.9 from 12 on Capterra
- Awards
- None found.
- Runs on
- Xero, MYOB AccountRight, Exo, Essentials and Acumatica, QuickBooks Online, NetSuite, Dynamics, Sage 300, Sage Intacct, SAP Business One, Pronto Xi, Attaché.
- Late fees and interest
- None found. No late fee or interest function appears in the ezyCollect help center or relaunch materials; card surcharging is the only charge mechanic documented.
- Does best
- Live credit intelligence from Experian applied to your own aged balances and terms, so a customer is screened before the terms are extended rather than chased after.
- Customers
- Named on its website: Feral Brewing, Hampers with Bite and Skillinvest. Feral Brewing's case study reports overdue accounts cut by over 50%.
The escalation path is explicit and priced. In-app demand letters cost A$49 plus GST each, and beyond that the tool refers the debt to third-party collection partners on commission from 25 percent of amounts recovered.
Limitations with ezyCollect. No late fee or interest anywhere in the product. Pricing is banded by active debtors with a setup fee from A$900 rising to A$3,900 on the higher tiers, and SMS, mail and fax are charged on top. Taking payments carries a monthly gateway fee of A$90 plus GST.
Customers who run past the end of a workflow receive no further automated follow-up. A Xero App Store reviewer reports the quoted price came in near three times the advertised rate, so get the quote in writing.
Best suited for: An Australian wholesale or distribution business that wants Experian credit screening before terms go out. It has no late fee or interest, and the pricing adds a setup fee from A$900 plus charges for SMS and mail.
5. Kolleno, best for cash application and reconciliation over reminders
Kolleno is an order-to-cash platform for NetSuite or SAP teams, from $650 per user a month on BusinessPay ($545 on annual billing).
What is it best for?
Choose Kolleno if your bottleneck is cash application and reconciliation rather than the reminder itself.
- Fits
- Mid-market and enterprise order-to-cash teams. Kolleno BusinessPay is for turnover under £1m, Business Plus £1m to £100m, Enterprise £100m to £1bn.
- Regions
- London-based, founded 2020, sells internationally.
- Entry cost
- $650 per user a month on BusinessPay with a one-user minimum, or $545 per user on annual billing; Business Plus $1,245 per user with a two-user minimum. Kolleno Enterprise tiers are quoted.
- Rated
- 4.9 from 117 G2 reviews; 5.0 from 18 Xero App Store reviews; 5.0 from 8 on Capterra
- Awards
- None found.
- Runs on
- NetSuite, SAP S/4HANA and Business One, Sage Intacct, Dynamics 365, Workday, Oracle JD Edwards, Epicor, Infor, Odoo, Zuora, Xero, QuickBooks Online, Salesforce.
- Late fees and interest
- None found. No Kolleno feature page or help article documents a late fee or interest charge.
- Does best
- Cash application. Email remittance parsing, BAI2, NACHA and ISO 20022 bank files, match scoring, one-to-many matching, credit-note offsets and NetSuite multi-currency journal entries.
- Customers
- Named on its website: Wise, Deel and Laundryheap. Laundryheap's case study reports 94% of payments collected on time.
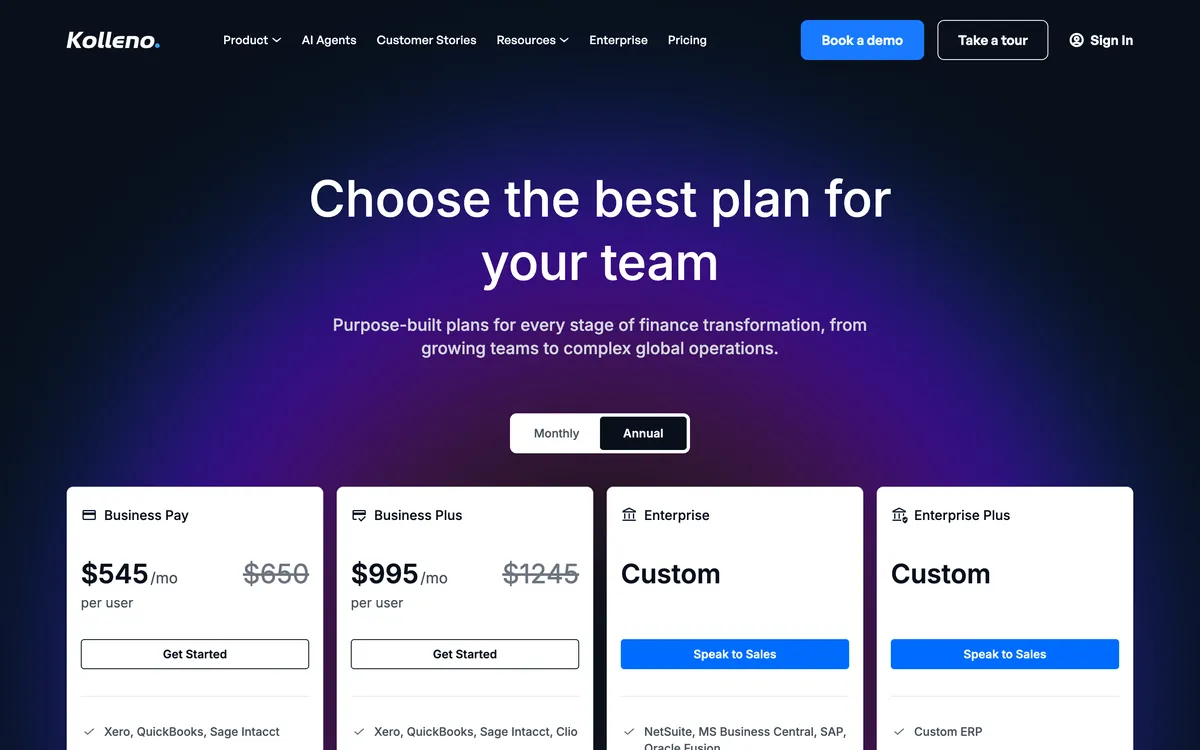
Limitations with Kolleno. No late fee or interest mechanic, so enforcement stays a manual job or an ERP one. Per-user pricing from $650 a month multiplies with the size of the team and sits above the small-business band. Reviewers report they cannot always find features, and ask for more customizable reporting.
Best suited for: An order-to-cash team on NetSuite or SAP whose bottleneck is cash application and reconciliation. Per-user pricing from $650 a month sits above the small-business band, and there is no late fee mechanic.
6. Satago, best for credit scores and optional invoice finance
Satago is a credit reporting and chasing tool with optional invoice finance for Sage 50 or Xero teams, from £25 a month inside Sage 50, the vendor's published GBP price.
What is it best for?
Choose Satago if you run Sage 50 or Xero and want customer credit scores, suggested limits and optional invoice finance from the provider that runs your chasing.
- Fits
- UK businesses in the Sage and Xero ecosystem. Satago publishes no revenue band; its value metric is credit reports and reminder volume.
- Regions
- United Kingdom. Satago's footprint is UK-only on both the software and the lending side.
- Entry cost
- £25/mo on the Standard tier embedded in Sage 50 and £45/mo on Plus; standalone Basic £45/mo, Premium £80/mo, Platinum £200/mo. Satago Plus is included with selected Sage 50 subscriptions, and which ones is not published.
- Rated
- 4.93 from 92 Xero App Store reviews on the UK listing.
- Awards
- None found.
- Runs on
- Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent.
- Late fees and interest
- Optional. Satago adds an optional late fee to reminder emails, calculated in line with statutory limits, and does not document posting it to the ledger.
- Does best
- Pairing automated chasing with credit reports, customer credit scores and suggested credit limits, with invoice finance available from the same provider.
Satago is a hybrid: automated credit control on one side, single and full invoice finance on the other. Roughly half the public site serves the lending channel, which is worth knowing before you treat it as a pure software purchase.
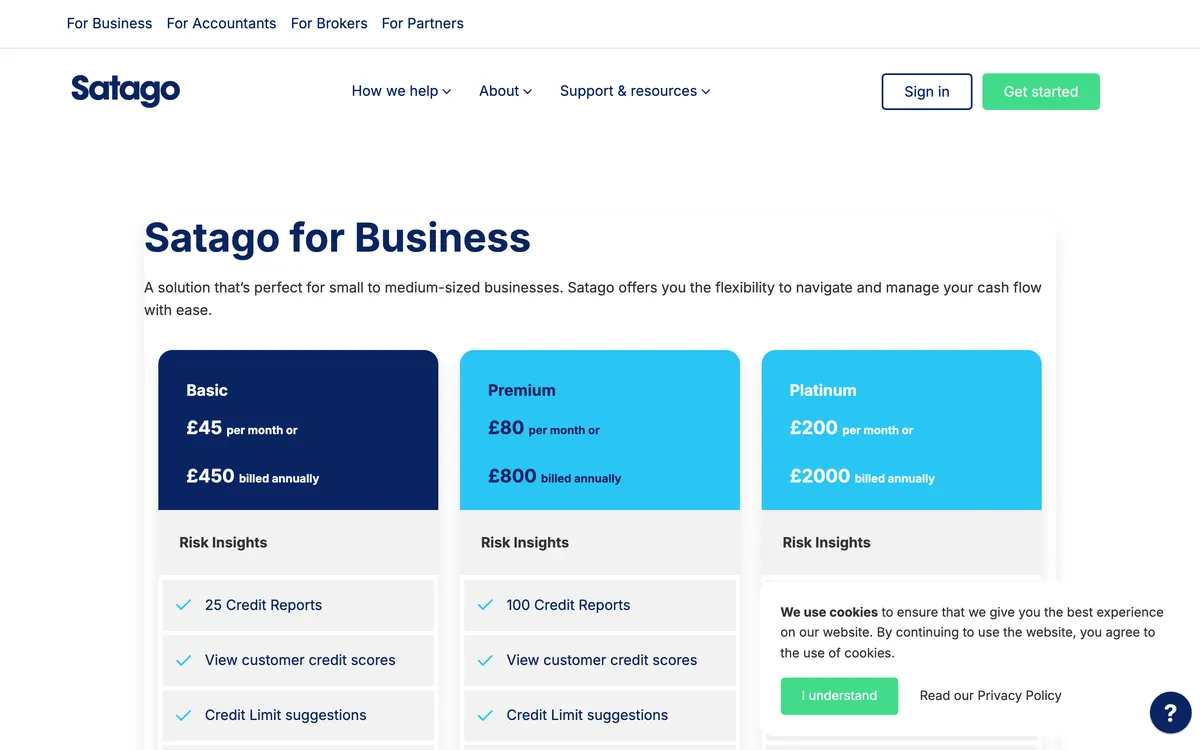
Limitations with Satago. Its optional late fee is added to reminder emails, and posting it to the ledger is not documented. The standalone Basic tier caps email reminders at 100 a month and SMS starts only on Premium.
Which Sage 50 subscriptions include Satago's Plus tier at no extra cost is not published, so the real Satago price sits between nothing and £45 a month.
Best suited for: A UK team on Sage 50 or Xero that wants credit scores and optional invoice finance from the provider that runs its chasing. No late fee or interest mechanic could be confirmed, and the standalone Basic tier caps email reminders at 100 a month.
Which tools check credit before terms go out?
Chaser, CreditorWatch Collect, ezyCollect, Kolleno and Satago put credit data in front of you on their standard plans. Paidnice runs native credit checks from each customer's payment behavior on every plan, and Creditsafe bureau checks through the API on the Custom plan.
Chaser carries a full credit report, supplied by Creditsafe and sitting inside the app rather than behind a separate login. It holds a credit score with a recommended credit limit, the customer's own payment score, their credit event history, and Companies House filing and director data, with continuous monitoring and a late payment predictor layered on top.
A credit controller uses a Creditsafe recommended credit limit three ways: to set the ceiling on an account before the first order ships, to decide whether a customer asking for extended terms should get them, and to react to a credit event once monitoring is on.
The third use is the one that pays for the subscription, because a customer's score usually moves before their payment behavior does.
The others screen differently. CreditorWatch Collect surfaces payment scores from its parent bureau, and ezyCollect applies Experian data to your own aged balances.
Kolleno scores with its own AI plus bureau integrations, and Satago meters credit reports, scores and suggested limits by tier. Where the AI drafts or runs the chase itself rather than scoring risk, see the AI collections software guide.
Paidnice runs native credit checks from each customer's payment behavior on every plan, and Creditsafe bureau checks through the API on the Custom plan: an in-app Creditsafe check with a score and a limit, monitoring with alerts, and automatic flags on new customers. A business can bring its own Creditsafe account or use access Paidnice supplies, billed by usage.
On Essentials and Pro there is no bureau check, so a business that screens new customers against bureau data on those plans needs a bureau alongside it.
When should you buy a calling team instead of a workflow?
Buy a calling team instead of a workflow when the automated sequence has hit its floor, somewhere past the fourth or fifth message. A customer who has ignored four automated reminders is unlikely to respond to a fifth in a firmer tone, which is the point to move that account to a phone call.
CreditorWatch Collect is the only tool on this page that sells one. Its Call Console builds the day's calling queue automatically, and its paid Call Assist add-on puts trained local AR specialists on the calls, on rules you set, with every outcome logged. Call notes push back into Xero, so the conversation lands on the ledger.
It is a staffing cost. Call Assist runs A$195 a month for 20 calls, A$495 for 150 or A$795 for 400, on top of the software quote that follows the 14-day trial. Compare that with the cost of a part-time credit controller, not with a software subscription.
If nobody is chasing, buy the workflow. If a controller already chases and forty accounts still ignore her, a voice starts to look cheap.
How much does credit control software cost?
Credit control software on this page costs from £25 a month for Satago inside Sage 50 to $650 per user a month for Kolleno.
Chaser starts at US$259 (£199 in the UK), Paidnice at US$69 and ezyCollect at A$275 (last published; now hidden, request a quote) on annual billing. CreditorWatch Collect last reported A$89 a month by debtor count (now hidden, request a quote).
Four pricing metrics sit behind those numbers. Kolleno charges per user, so a credit control team of three multiplies the bill before anything is chased. Chaser charges by company turnover, so the price steps up as you grow rather than as you use more.
ezyCollect charges by active debtors and adds a one-off setup fee from A$900, rising to A$3,900 on the higher tiers. Paidnice is priced by invoice volume, not revenue: Essentials covers 2 team members, and Pro has unlimited users with no per-seat fee.
Read the meters before you compare the headlines. Chaser bills SMS, letters and calls as credits and prices credit checks per report. Paidnice bills Creditsafe usage on top of its Custom plan. Satago's entry tier includes three full credit reports a year, which is a different product from unlimited chasing.
Which credit control software fits your use case?
Start with the job you need covered, then check the ledger. Each row names the tool on this page whose published features match that job.
| Use case | Start with | Why |
|---|---|---|
| Xero or QuickBooks Online, late fees and interest per customer group | Paidnice | Fee and interest policies per customer group, posted to the ledger, from US$69 a month |
| Reminders and statements only, no late fees | Paidnice or Chaser | Both run reminder sequences and statements; Paidnice sends statements on any schedule, Chaser monthly on a fixed day |
| Credit checks on the standard plan | Chaser | Creditsafe credit reports, monitoring and a recommended limit inside the app |
| Australian business that wants people making the calls | CreditorWatch Collect | Call Assist puts trained AR specialists on the calls, from A$195 a month |
| Australian trade or wholesale seller screening new accounts | ezyCollect | Experian credit data applied to your own aged balances |
| NetSuite or SAP order-to-cash team | Kolleno | Cash application, remittance parsing and bank file matching |
What do buyers ask before they shortlist?
Buyers shortlisting credit control software ask what the best tool is, which tools charge late fees, which connect to their ledger, which check credit and how the category differs from debt collection.
What is the best credit control software?
The best credit control software depends on the part of the job you want covered. Paidnice posts per-group late fees on Xero or QuickBooks Online, Chaser pairs Creditsafe checks with chasing, CreditorWatch Collect adds people making calls, ezyCollect screens Australian trade buyers, Kolleno handles cash application, and Satago adds invoice finance on Sage 50.
Which credit control tools apply a late fee automatically?
Paidnice and Chaser apply a late fee automatically. Chaser runs one global rule that cannot vary by customer group and raises no fee on payment-plan or partially paid invoices; Paidnice runs a policy per customer group and raises the charge on the ledger as Draft or Approved. The others document no fee function.
Which credit control software works with Xero, QuickBooks and Sage?
Every tool here works with Xero. QuickBooks Online works with Paidnice, Chaser, CreditorWatch Collect, ezyCollect and Kolleno, and Satago lists QuickBooks. Sage works with Chaser, ezyCollect (Sage 300, Sage Intacct), Kolleno (Sage Intacct) and Satago, and Paidnice reaches Sage Intacct on its Custom plan only.
How much does credit control software cost?
Credit control software on this page costs from £25 a month for Satago inside Sage 50 to $650 per user a month for Kolleno. Paidnice starts at US$69 a month and Chaser at US$259 (£199 in the UK).
What credit control software checks credit before terms go out?
Chaser, CreditorWatch Collect, ezyCollect, Kolleno and Satago carry credit data on their standard plans. Paidnice runs native credit checks from each customer's payment behavior, and Creditsafe bureau checks through the API on the Custom plan.
What software do finance managers use for credit control?
Finance managers at small and mid-size businesses use a credit control tool connected to their ledger, such as Paidnice, Chaser, CreditorWatch Collect, ezyCollect, Kolleno or Satago. Large B2B finance teams use enterprise order-to-cash and credit management platforms such as HighRadius or Esker, inside the ERP.
Is credit control software the same as debt collection software?
No, credit control software is not debt collection software. Credit control works your own ledger and customers until you decide the debt is not coming in; a collection agency works it after that and takes a percentage. Several tools here refer the debt onward on commission, which is a handover rather than a feature.
Related comparisons
Buyer's guide
Best accounts receivable software
Where the same job is sold as accounts receivable automation instead.
United Kingdom
Best credit control software for UK SMEs
Statutory interest, chasing and credit risk, compared for the UK.
How-to
The credit control process
The steps from credit check to escalation, and who owns each one.
Measurement
Credit control metrics
What to measure before and after you switch a tool on.