The six best debtor management software tools for UK businesses in 2026 are Paidnice, Chaser, Credit Hound, Satago, Kolleno and Upflow, compared on the debtor workspace each one gives a credit controller and on whether the tool applies UK statutory interest itself. Entry prices run from £20 per user a month to $650.
| Tool | Best for |
|---|---|
| Paidnice | a UK business on Xero or QuickBooks Online that wants customers grouped and charged by policy, any size up to $50m a year, or 50,000 invoices a year |
| Chaser | a UK team that wants Creditsafe credit checks beside a shared chasing queue, up to £4m on the entry tier |
| Credit Hound | a Sage-first UK team that wants a worklist built around promises and disputes, priced per user |
What debtor management software is (and what it is not)
Debtor management software gives a credit controller one workspace for every account that already owes money: an ordered worklist, promise-to-pay records, disputes with reasons, notes held against the customer, and the reminders and statements going out. Some tools also raise the statutory interest charge when nothing arrives.
It sits on top of the ledger. Xero, QuickBooks Online or Sage still holds the invoices, and the workspace reads them, so what it shows and what the ledger shows should agree on the same morning.
What it is not:
- Not the ledger or the invoicing system. Invoices are raised and reconciled there.
- Not a debt collection agency. Chaser hands a debt to an integrated collections partner, which is a commercial handover with a commission attached.
- Not invoice finance, although Satago sells finance from the same provider that runs its chasing.
- Not a separate discipline from credit control. Credit control also covers terms and credit checks; debtor management is the surface a controller works in each morning.
Reminders and statements alone are still a full use case, and the charge is optional.
How this list was put together
This list helps a UK credit controller choose one workspace for every account that owes money, on Xero, QuickBooks Online or Sage.
| What we checked | Where the evidence came from |
|---|---|
| An ordered worklist, and an aged view that agrees with the ledger on the same morning | Vendor product pages and help documentation for each workspace |
| A promise to pay recorded with amount, date and who gave it | Vendor help pages on promise-to-pay tracking |
| Disputes with a reason code, and notes held against the customer | Vendor help pages on disputes and account notes |
| Escalation a person controls: stop, freeze or hand over | Vendor workflow documentation |
| UK statutory interest under the Late Payment of Commercial Debts (Interest) Act 1998, raised by the tool | Vendor help pages on fees and interest |
| Rating and review count | The Xero App Store, the Sage UK Marketplace or G2; Credit Hound's public base is twelve reviews |
What is the best debtor management software for UK businesses?
Paidnice is the best debtor management software for a UK business on Xero or QuickBooks Online that wants customers grouped and charged statutory interest by policy.
The statutory calculation is covered on the UK credit control comparison.
How do the six UK debtor management tools compare?
Read the promise-to-pay row first. It is the row that separates a debtor workspace from a sending engine, and three of the six carry a Not documented in it.
 |
 |
 |
 |
 |
 |
|
|---|---|---|---|---|---|---|
| Best for | Grouping and charging customers by policy on Xero or QuickBooks Online | Creditsafe checks beside a shared chasing queue, to £4m on entry | A Sage-first worklist built around promises and disputes | Sage 50 or Xero teams wanting credit data with chasing | Order-to-cash teams on NetSuite or SAP | Analytics-led teams managing debtors by metric |
| Revenue fit | Any size up to $50m a year, or 50,000 invoices a year | Compact under £4m, Core from £4m, Complete to £100m | Not published | Not published | Under £1m on BusinessPay, tiers to £1bn and above | Gross invoice value tiers, up to $10m through above $100m |
| From (monthly) | £49 | £199 | £20 per user (Sage Accounting) | £45 (£25 inside Sage 50) | $650 per user | Not published |
| Ledger integrations | Xero, QuickBooks Online and newer ledgers such as Rillet and Campfire (closed testing) on every plan; Sage Accounting and other ERPs on Custom | Xero, QuickBooks, Sage, NetSuite, Dynamics 365 Business Central | Sage 50, Sage 200, Sage Intacct, Xero | Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent | NetSuite, SAP, Sage Intacct, Business Central, Xero, QuickBooks Online | Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora |
| Debtor workspace | Yes (customer groups and policies) | Yes (shared chasing workspace) | Yes (task list, promises, disputes) | Yes (chasing and risk view) | Yes (unified workspace, disputes) | Yes (analytics and workflows) |
| Promise-to-pay tracking | Not documented | Not documented | Yes (promised cash report) | Not documented | Yes | Yes (auto-detected) |
| Late fee grain | Yes (per customer group) | Yes (one set of rules, account-wide or for selected debtors) | None found | Optional, added to reminder emails | None found | No (via your ERP only) |
| Statements | Yes (any schedule) | Yes (monthly, fixed day) | None found | Yes | Yes (in the portal) | Portal PDF statement, no scheduled send |
| Payment plans | Yes (on Pro) | Yes | None found | Not documented | Yes | No |
| Portal | Yes | Yes | No (PayThem payment links only) | Not documented | Yes | Yes |
| Credit checks | Yes: native checks from payment behaviour, plus Creditsafe via API on the Custom plan | Yes (Creditsafe) | No (limits read from your ledger) | Yes (credit reports and limits) | Yes (AI scores, bureau integrations) | Yes (light scoring) |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | None No named AI feature | None No AI feature found | Advanced Insights, Copilot drafts and an autonomous Agent; most AI features are in the subscription and fully automated agent runs are billed separately by token usage | Advanced Collections and cash application agents, from suggest-only to autonomous (Collections Agent from Scale, Cash Application Agent from Accelerate) | |
| Rated (source, count) | 5.0 (84, Xero App Store) | 4.98 (374, Xero App Store) | 5.0 (12, Sage UK Marketplace) | 4.93 (92, Xero App Store) | 4.9 (117, G2) | 4.8 (235, G2) |
"Not documented" means the vendor does not document it. "Not published" means no price is printed. "None found" means no evidence either way. Prices are the vendor's published from-price.
Five of the tools on this page in four checked facts
- Four of the five print a monthly price: Satago from £45, Paidnice from £49 (US$69), Chaser from £199 and Kolleno from US$650. Upflow quotes.
- Each published price grows with something different: a flat tier (Satago), invoice volume (Paidnice), revenue band (Chaser) and users (Kolleno).
- Satago adds an optional late fee to its reminder emails, and two of the five apply a late fee themselves: Paidnice (per customer group) and Chaser (one set of rules).
- AI that handles collections work or customer replies: Paidnice, Kolleno and Upflow. No AI in receivables: Satago.
We checked each tool's own pricing, integration and help pages on October 26, 2026. "None found" in the data means the vendor's pages do not show the feature. Credit Hound is not in our checked dataset yet.
1. Paidnice, best for charging by policy
Best for: A UK business on Xero or QuickBooks Online that wants customers grouped and charged by policy, any size up to $50m a year, or 50,000 invoices a year.
What is Paidnice best for?
For a UK business on Xero or QuickBooks Online that wants overdue accounts grouped, chased and charged statutory interest without anyone doing the base-rate maths manually.
- Fits
- UK businesses on Xero or QuickBooks Online of any size up to $50m a year, or 50,000 invoices a year, with or without a credit controller
- Regions
- United Kingdom, Australia, New Zealand, United States, Canada, South Africa
- Entry cost
- £49 (US$69) a month on Essentials, covering 150 invoices, 600 emails and up to 2 team members; Pro from £74 (US$99) a month with unlimited users and no per-seat fee
- Rated
- 5.0 from 84 Xero App Store reviews; 4.9 from 14 on Capterra
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero and QuickBooks Online on every plan, plus Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive and Zapier. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice's closed testing program. NetSuite, Sage Intacct, Sage Accounting, MYOB, Dynamics 365 Business Central and other ERPs connect on the Custom plan
- Statutory late fees
- Yes. A Bank of England base rate toggle applies the base rate plus your own percentage, using the correct base rate for each period an invoice spans, and policies sit under customer groups so different groups run different rules at once
- Does best
- Two charge types on the same customer group, an invoice late fee and a statement interest charge, both posted to the ledger
Paidnice is the enforcement layer on top of Xero and QuickBooks Online. Customers sit in groups, and each group carries its own reminder sequence, statement schedule including consolidated parent accounts, payment plans (on Pro), escalation and interest policy.
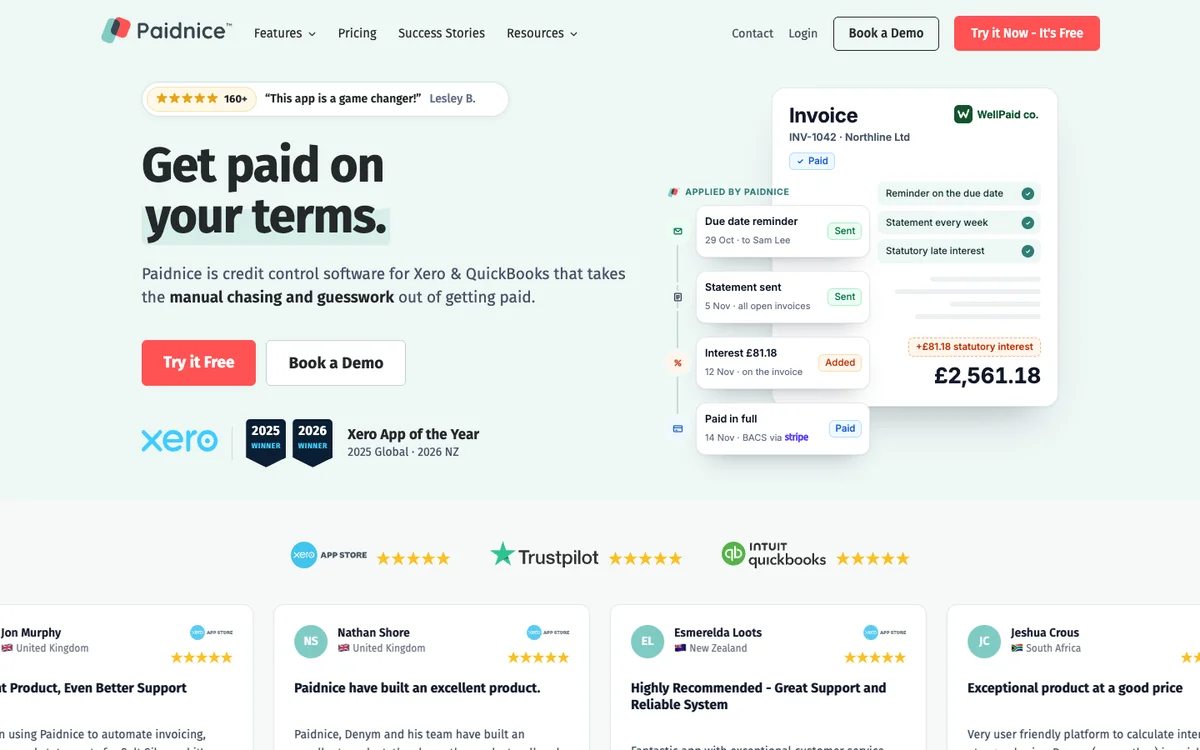
Reminders send by email and SMS from [email protected] on Essentials. Sending from your own domain starts on Pro, or reminders can go through a connected Gmail or Outlook (Microsoft 365) mailbox.
The interest rule is set once against a customer group, including a Bank of England base rate option, and the charge then appears on the account and lands on the ledger as Draft or Approved, so a controller reviews a document rather than working out a figure.
Limitations with Paidnice. Some payment features differ between Xero and QuickBooks Online, and the entry tier covers two team members, which matters more here than elsewhere because a debtor workspace is usually shared.
On the six workspace tests it is lighter than Chaser and Credit Hound: bureau checks only on the Custom plan, and neither a promise-to-pay record nor a dispute log could be verified, which makes it a policy engine a controller supervises rather than a screen a controller works in.
Its review base is smaller than Chaser’s, 84 reviews against 374.
2. Chaser, best for Creditsafe and shared queue
Best for: A UK team that wants Creditsafe credit checks beside a shared chasing queue, up to £4m on the entry tier.
What is Chaser best for?
For a UK finance team with a named credit controller that wants Creditsafe credit checks and multi-channel chasing running from one shared workspace.
- Fits
- UK-centred businesses with a named credit controller; the entry tier is priced for revenue under £4m, and the tiers run to £100m
- Regions
- UK-registered, trading since 2014, sells worldwide
- Entry cost
- £199/mo on Compact for revenue under £4m with 4 users; Core £599/mo under £10m; Complete £899/mo to £100m.
- Rated
- 4.98 from 374 Xero App Store reviews; 4.3 from 71 on G2
- Awards
- Finalist, UK Small Business App Partner of the Year, Xero Awards 2023
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Business Central, AccountsIQ, SAP, HubSpot, Gmail, Outlook
- Statutory late fees
- Yes. Four calculation types including a Bank of England base rate type, recalculated daily, but one set of late-fee rules, across the account or for selected debtors, not tied to schedules, with no documented way to run different rules per group, and no fee is raised on payment-plan invoices. Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero
- Does best
- Creditsafe credit checking and monitoring in the same tool as email, SMS and letter chasing
- Customers
- Named on its website: Pact Coffee, Huttie and TaxAssist. Huttie's case study reports £15,000 of old debt recovered.
The workspace is shared, so two or three controllers work the same debtor list rather than trading spreadsheets. Reminders go out from the team's own Gmail or Outlook mailbox, with SMS, posted letters, a payer portal, dispute flagging and an integrated collections partner behind them.
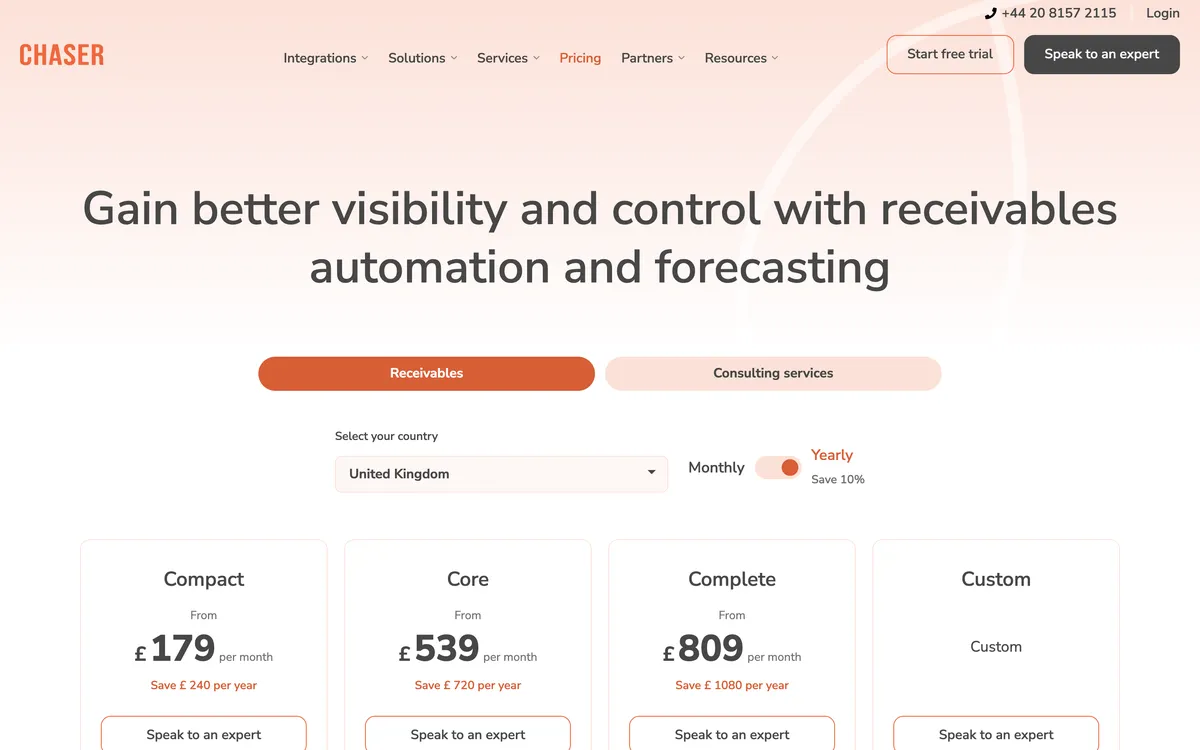
A Creditsafe report sits in the same screen as the debtor list, which puts a customer's risk beside what they owe; the report itself is broken down in the review of the best credit management software.
Limitations with Chaser. It has one set of late-fee rules, across the account or for selected debtors, not tied to schedules, and documents no way to run different rules per group.
No fee is raised on a payment-plan invoice either, and Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero. Statements go monthly only, on a fixed day, Compact caps the team at four users, and the entry price is tiered by company turnover rather than by how much work the ledger actually is.
3. Credit Hound, best for promises and disputes
Best for: A Sage-first UK team that wants a worklist built around promises and disputes, priced per user.
What is Credit Hound best for?
For a Sage 50 or Sage 200 finance team that wants a daily chase-and-dispute worklist telling it who to call, rather than a fee engine.
- Fits
- Sage-first UK finance teams. No revenue band published; the product is priced per user
- Regions
- Core market is the UK Sage channel, with Sage 50 connectors for UK and Ireland, the US and Canada, and pricing published in GBP, EUR, USD, CAD, AUD and ZAR
- Entry cost
- £20 per user a month on Sage Accounting; £51 for the first user then £35 each on Sage 50 and Xero; £82 then £50 each on Sage 200; the PayThem payment module is £38/mo on top.
- Rated
- 5.0 from 12 reviews on the Sage UK Marketplace; 4.5 from a single review on G2, which is too small a base to read as a quality signal
- Awards
- Not published
- Runs on
- Sage Accounting, Sage 50cloud, Sage 100cloud, Sage 200 Standard and Professional, Sage Intacct, Infor SunSystems Cloud and Xero. No QuickBooks Online connector
- Statutory late fees
- None found. No interest, late fee, surcharge or fixed-sum function appears in the vendor's product pages, cloud feature list, FAQs, product guide or Sage-hosted brochure
- Does best
- Structured dispute management with automated follow-ups, and promise-to-pay tracking with a promised-cash view
Credit Hound is built for the Sage reseller channel, and it is the deepest debtor workspace in this comparison.
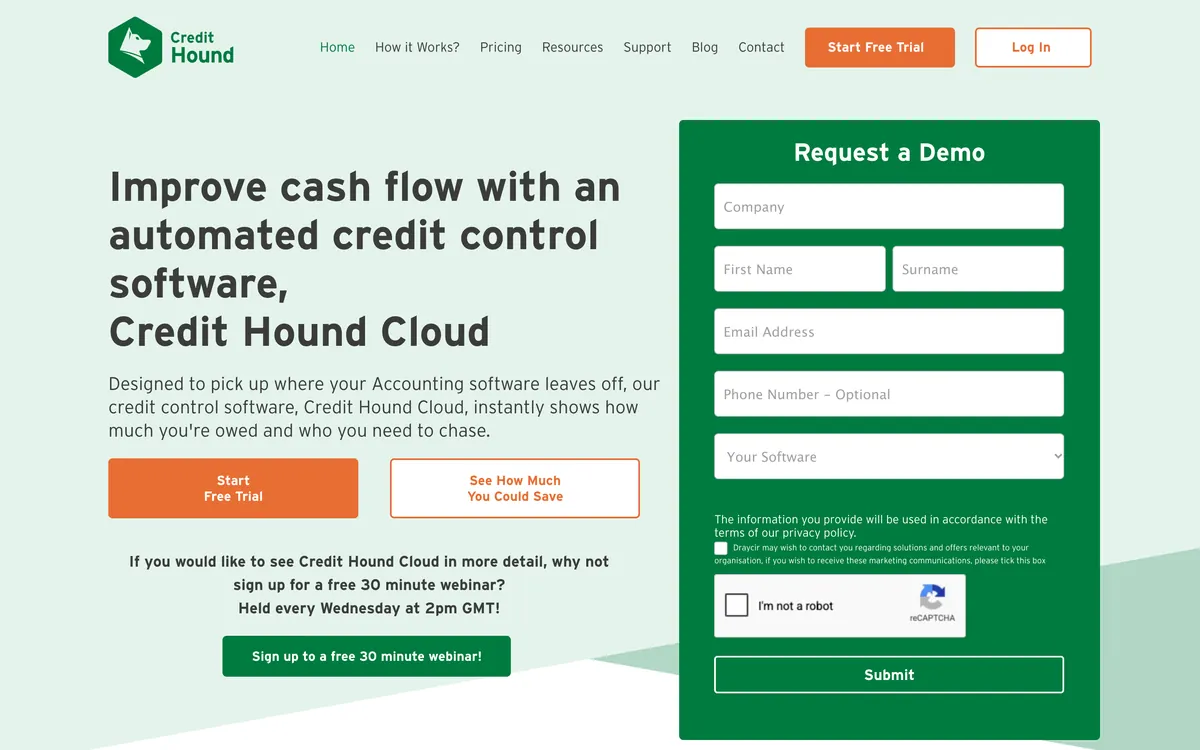
It gives a credit controller a task dashboard that says who to call and why, promise-to-pay records that roll into a promised-cash report, dispute logging with reasons, internal and customer-facing notes with automated dispute notifications, and automatic account freezes on overdue customers.
Reporting matches the worklist: aged debt analysis, call-back analysis, promised cash, dispute analysis, account summary and user activity, filtered and exported to Excel.
Pricing is published openly, which is unusual in this channel.
Limitations with Credit Hound. It chases; it does not charge. No late fee, interest, statutory interest or fixed sum appears in the vendor's documentation, and nothing describes writing a charge back to the ledger.
Promise-to-pay is a note and a report rather than a scheduled instalment agreement. There is no QuickBooks Online connector, payments are a separate £38 a month module, per-user pricing on Sage 200 and Xero scales badly, and the whole public review base is 12 reviews.
4. Satago, best for Sage 50 credit data
Best for: Sage 50 and Xero teams that want credit data with their chasing, no revenue band published.
What is Satago best for?
For a Sage 50 or Xero business that wants credit reports and invoice finance from the same provider that runs its chasing.
- Fits
- UK businesses in the Sage and Xero ecosystem. No revenue band published
- Regions
- United Kingdom only
- Entry cost
- £25/mo Standard and £45/mo Plus inside Sage 50, with Plus included on selected Sage 50 subscriptions; standalone £45/mo Basic, £80 Premium, £200 Platinum.
- Rated
- 4.93 from 92 Xero App Store reviews, UK listing
- Awards
- Not published
- Runs on
- Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent
- Statutory late fees
- Optional. Late fees are calculated in line with statutory limits and added to payment reminders once an invoice is overdue
- Does best
- Credit reports, customer credit scores and suggested credit limits bundled into the same subscription as the chasing, with invoice finance from the same provider
What Satago puts in front of a controller is a risk view rather than a task list: the customer's credit score and the direction it is moving, sitting next to the balance they owe.
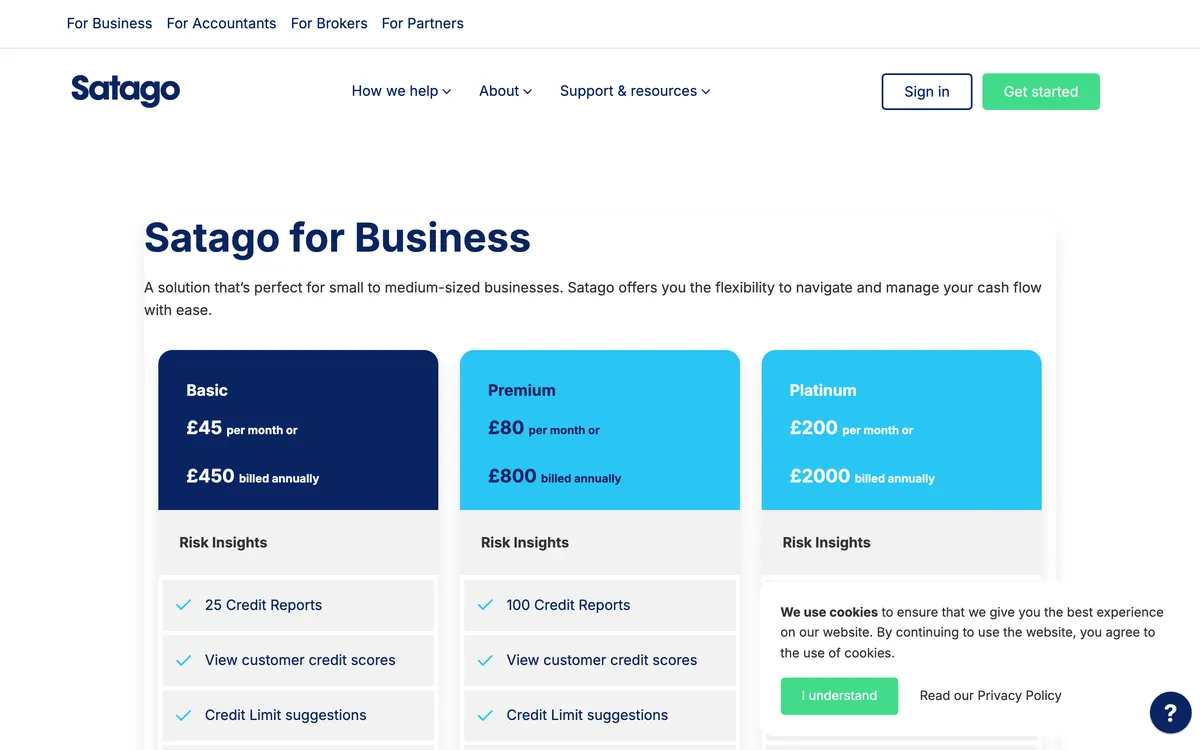
The cheapest way in is the edition embedded in Sage 50 at £25 a month, which covers reminders, statements, customer grouping and scheduling; the pricing and the invoice finance side are set out on the credit control software comparison.
Limitations with Satago. There is a risk view but no worklist: no promise-to-pay record, no dispute reason code and no escalation control could be verified, so a controller working it is still ordering the day themselves.
Basic caps email reminders at 100 a month and does not list own-inbox sending, your own inbox starts at the £80 Premium tier, and Satago adds an optional late fee to its reminder emails.
5. Kolleno, best for remittance parsing
Best for: Order-to-cash teams on NetSuite or SAP.
What is Kolleno best for?
For a NetSuite or SAP order-to-cash team that needs remittance parsing and bank-file cash application as well as a debtor list.
- Fits
- Order-to-cash teams: BusinessPay for turnover under £1m, Business Plus £1m to £100m, Enterprise £100m to £1bn
- Regions
- London head office, founded 2020, selling internationally
- Entry cost
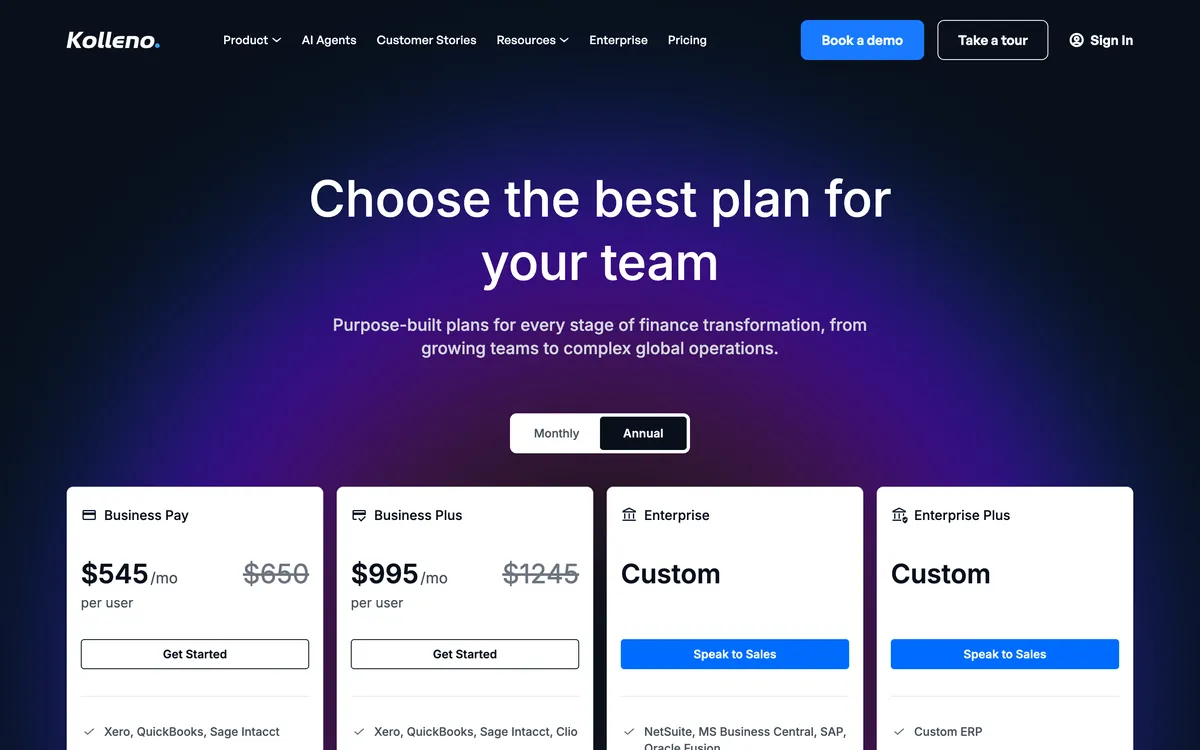
- $650 per user a month on BusinessPay, $545 on annual billing, minimum one user, for turnover under £1m; Business Plus $1,245 per user.
- Rated
- 4.9 from 117 G2 reviews; 5.0 from 18 Xero App Store reviews; 5.0 from 8 on Capterra
- Awards
- G2 Best Software Awards 2024
- Runs on
- NetSuite, SAP S/4HANA and Business One, Sage Intacct, Business Central, Workday, Oracle JD Edwards, Epicor, Infor, Odoo, Zuora, Xero, QuickBooks Online
- Statutory late fees
- None found. No feature page or help article documents a late fee or interest calculation
- Does best
- Cash application, with email remittance parsing, BAI2, NACHA and ISO 20022 bank files, match scoring and NetSuite multi-currency journal entries
- Customers
- Named on its website: Wise, Marshmallow and Laundryheap. Laundryheap's case study reports 94% of payments collected on time.
Kolleno gives a mid-market team one unified workspace rather than a per-person view, and the part of it that matters to a controller is the deduction handling: chargebacks and short payments are classified by reason code and ranked, so the disputed portion of the ledger arrives already sorted.
Its cash application depth, which is the reason most buyers reach it, is covered on the credit control software comparison.
Its collections agent works a policy without a person in the loop. Promises to pay are recorded in the workspace.
Limitations with Kolleno. The workspace is priced per seat from $650 a month on BusinessPay, which is the wrong shape for a UK team that wants three people in the same debtor list, and the second tier doubles it. Kolleno matches payments to invoices (auto-reconciliation) on Enterprise only, by quote; BusinessPay at $650 per user a month does not include it. Xero and QuickBooks connect on BusinessPay and Business Plus; NetSuite and SAP start on Enterprise.
Nothing documents a late fee or interest calculation. The default contract term is 24 months if the order form is silent, renewing for 12 months with 90 days' notice, and fees are non-refundable. Reviewers name navigation and reporting depth as the recurring weak points. Kolleno includes 100 to 600 calls a plan. Its pricing page does not say which actions a workflow can hold.
6. Upflow, best for managing debtors by metric
Best for: Analytics-led finance teams, quoted in five gross invoice value tiers from up to $10m to above $100m.
What is Upflow best for?
For a finance team that manages debtors by metric and wants countback DSO and collection effectiveness measured before it automates anything.
- Fits
- B2B finance teams that manage by metric, quoted in five tiers by gross invoice value, from up to $10m on Starter to above $100m on Enterprise
- Regions
- New York head office, Paris origin, customers in 30-plus countries
- Entry cost
- Not published. Upflow prints no figures and quotes five tiers by gross invoice value; its pricing FAQ mentions a free Discover plan for analytics, but it is not among the plan cards. Upflow's last published prices were $440 a month for Grow and $880 for Scale
- Rated
- 4.8 from 235 G2 reviews; 4.5 from 15 on Capterra · Xero App Store listing
- Awards
- Not published
- Runs on
- Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora
- Statutory late fees
- No, via your ERP only. Upflow's own documentation points the job back to the ERP and there is no native computation
- Does best
- Collections analytics, with countback DSO against best possible DSO, collection effectiveness and an at-risk rate above 90 days
- Customers
- Named on its website: Lattice, Vercel and Front. Lattice's case study reports 99% collection with one person in AR.
Upflow answers the question a finance director asks rather than the one a controller asks: its dashboards report on the debtor book by workflow, country or account manager, and the credit control software guide works through which of those measures are worth managing to.
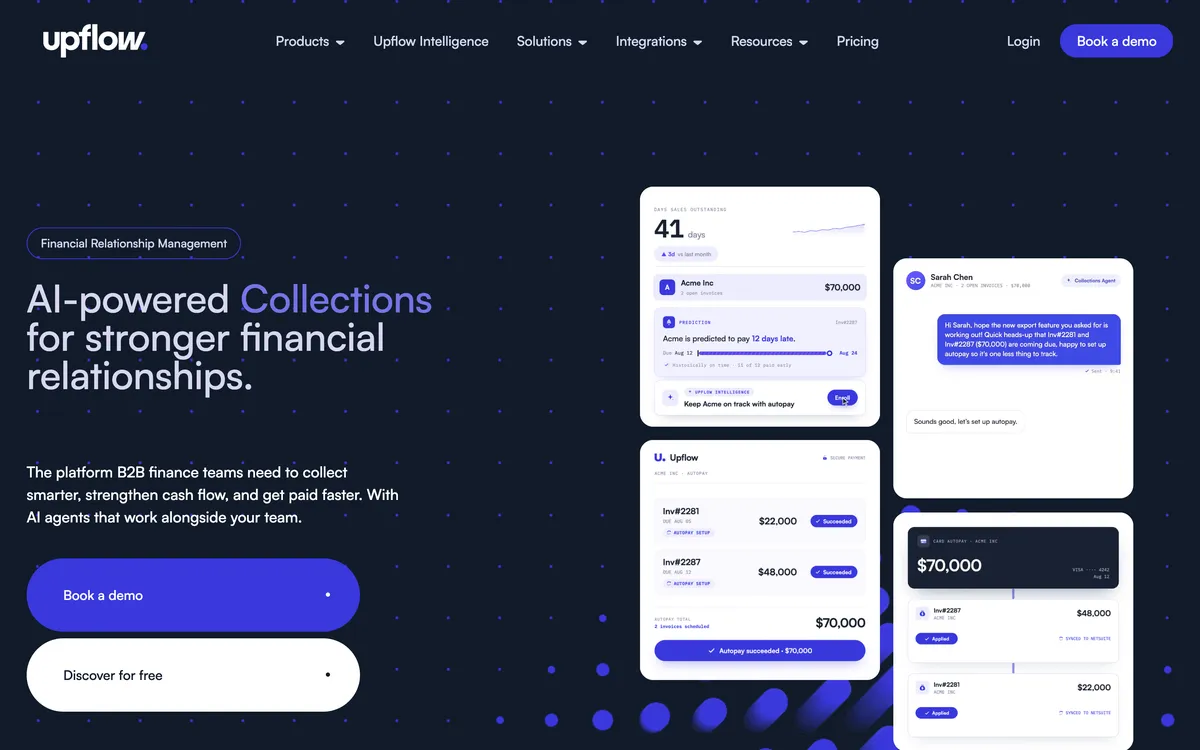
Promises and disputes are inferred from replies rather than entered by the controller, which captures the fact and loses the reasoning behind it.
Instalment plans are absent, leaving customer-initiated part payments. Automatic actions run once a day on business days only, sending through your own SMTP costs open and click tracking, and Upflow's last published prices were $440 a month for Grow and $880 for Scale, and current prices are hidden and must be requested.
What happens when a promise to pay breaks?
A promise to pay holds three facts: the amount, the date, and the name of the person who gave it. Held properly it becomes a cash forecast.
Three of the six record one against the account. Credit Hound holds a promise-to-pay record that rolls into a promised-cash report, so a controller can see committed cash for the week separately from the aged total.
Kolleno records promises inside its workspace. Upflow detects them automatically out of the customer's reply, which removes the step where a controller forgets to log the call. Paidnice, Chaser and Satago do not document the capability.
What happens on the morning after a promised date passes with no money in the account?
Nothing automatic, in any of the six. No vendor here documents a trigger that fires on a broken promise specifically. What differs is whether the break is visible. On Credit Hound the promised-cash report is the place the gap shows, and its automatic freeze on overdue accounts is triggered by the overdue status rather than by the broken promise.
On Upflow the promise is attached to the invoice, so the account rejoins the workflow as an ordinary overdue balance. Everywhere else the broken promise exists only if a person wrote it down and a person goes back to look.
Where should a dispute reason code live?
Few finance teams can produce their disputed debt by reason, and the difference is whether the dispute is a flag or a coded record on the invoice.
A flag stops the chase. A reason code stops the chase and shows you, at the end of the quarter, that eleven of your fourteen disputes were delivery shortfalls on one product line, which points to a warehouse problem.
Credit Hound logs disputes with reasons, notifies on them automatically and reports on them as dispute analysis, which is the most structured treatment in this set. Kolleno classifies deductions and chargebacks by reason code and ranks them for the controller. Chaser flags a disputed invoice inside the shared workspace.
Upflow surfaces disputes rather than asking anyone to log them. Paidnice takes a different route entirely: a reference filter lifts one disputed invoice out of a policy without moving the customer or switching the policy off, which is a suppression tool rather than a dispute record.
Who should decide when to escalate an overdue account?
Credit Hound freezes an account automatically once it is overdue, which puts the decision in the rule rather than in the controller. Chaser hands the debt to an integrated collections partner, so the escalation is a commercial handover with a commission attached.
Kolleno's agent works a collections policy on its own, which is the furthest any of the six goes towards taking the decision out of human hands. Upflow keeps calls and tasks manual, so escalation is always something a person did.
Paidnice runs escalation through manual task workflows, which can route escalation to any collection agency, solicitor or partner, and through the charge itself, which is the quieter form of escalation: the account stops being free to sit on before anyone has to make a phone call about it.
What survives when a credit controller leaves?
A credit controller resigns on a Friday, and by Monday most of what they knew was never written down anywhere the software could see.
Credit Hound keeps internal and customer-facing notes against the account and reports on user activity, so the record of who did what is queryable rather than remembered.
Kolleno's workspace is unified across the team by design. Upflow's history sits on the account, though its dispute and promise records are inferred from replies rather than typed by the controller, which means the reasoning behind them is not captured.
Chaser reminders send from the team's own Gmail or Outlook mailbox, which is why customers reply to them, and it also means the reply thread lives in a mail account.
The chasing workspace is shared, so the record of the sequence survives, but the conversation a customer had with a named person is only as portable as that mailbox.
How much does debtor management software cost in 2026?
Published UK entry prices: Credit Hound £20 per user a month on Sage Accounting, Satago from £45 (£25 inside Sage 50), Paidnice £49 (US$69), Chaser £199. Kolleno publishes $650 per user. Upflow's last published prices were $440 a month for Grow and $880 for Scale; current prices are hidden and must be requested from Upflow. Check current pricing with the vendor.
The tools with the deepest controller workspaces, Credit Hound and Kolleno, are the two priced per user, so the moment a second and third person work the same debtor list the bill multiplies.
Chaser steps by company turnover instead, so a growing ledger moves you up a tier whether or not the credit control team grew with it, and Compact caps that team at four users regardless. Paidnice steps by invoice volume on a flat tier with no per-seat fee above the entry plan.
Two of the six give a buyer nothing to plan with. Upflow quotes five tiers by gross invoice value and publishes no figure at any tier. Satago publishes tier prices without publishing which Sage 50 subscriptions include the Plus tier at no extra cost, so its real price is unknown until an account manager names it.
Which debtor management software fits your use case?
Choose by the job the controller does each morning, then check the ledger.
| Use case | Start with | Why |
|---|---|---|
| Xero or QuickBooks Online, statutory interest by customer group | Paidnice | Policies per customer group raise the charge on the ledger as Draft or Approved |
| Sage 50 or Sage 200 team that needs a daily worklist | Credit Hound | Task dashboard, promise-to-pay records and dispute reasons, from £51 a month for the first user and £35 for each extra user on Sage 50 |
| Several controllers sharing one debtor list, with credit checks | Chaser | Shared chasing workspace with a Creditsafe report on the same screen |
| Credit risk view and invoice finance | Satago | Credit scores beside the balance owed, with finance from the same provider |
| Deductions and cash application on NetSuite or SAP | Kolleno | Chargebacks and short payments classified by reason code, plus bank-file matching |
| Reporting debtor performance to a finance director | Upflow | Countback DSO and collection effectiveness dashboards |
Questions a finance manager asks
What is debtor management software?
Software that gives one person a workspace for every account that already owes you money: an ordered list of who to work today, the promises and disputes attached to those accounts, the reminders and statements going out against them, and, in some tools, the fee that is raised when nothing arrives.
Which of these six records a promise to pay?
Credit Hound, with a promised-cash report behind it, Kolleno inside its workspace, and Upflow by detecting the promise from the customer's reply. Paidnice, Chaser and Satago do not document it either way.
What happens when a promised payment date passes and no money arrives?
None of the six documents an automation that fires on a broken promise specifically. Credit Hound shows the gap in its promised-cash report and freezes accounts automatically once they are overdue; Upflow returns the invoice to the ordinary workflow. Everywhere else the broken promise is only as visible as the note somebody wrote.
Which tool handles disputes properly?
Credit Hound, on the evidence: dispute logging with reasons, automated notifications and a dispute analysis report. Kolleno codes deductions and chargebacks by reason and ranks them. Chaser flags disputed invoices in the shared workspace, and Paidnice suppresses a single disputed invoice from a policy with a reference filter rather than recording the dispute itself.
How much does debtor management software cost in the UK?
Credit Hound £20 per user a month on Sage Accounting and £51 plus £35 per extra user on Sage 50 and Xero; Satago from £45 (£25 inside Sage 50); Paidnice £49 (US$69) on Essentials; Chaser £199 for revenue under £4m; Kolleno $650 per user; Upflow's last published prices were $440 a month for Grow and $880 for Scale; current prices are hidden and must be requested from Upflow.
Check current pricing with the vendor.
Do these tools work with Xero?
All six connect. Credit Hound's Xero connector is priced per user at its Sage 50 rate (£51 for the first user, £35 for each extra), not the £20 Sage Accounting rate. Xero's own reminders send a basic email and hold no worklist, no promise record and no dispute reason, so they do not overlap with what is on this page.
Is debtor management the same as credit control?
Credit control describes the whole discipline including terms and credit checks, while debtor management is the working surface a controller opens every morning to deal with what is already outstanding.
For the wider shortlist across markets, the credit management software comparison sets out six tools by size, ledger and price.
Where to go next
Buyer's guide
Best credit control software UK
Six credit control systems compared on statutory interest, chasing and reviews.
Alternatives
Best Chaser alternatives
What a controller gets to work in, if Chaser's shared queue is not enough.
By accounting system
Best AR software for Xero
The wider Xero receivables field, beyond the debtor workspace question.
Small business
Best debt collection software for small business
When chasing is not enough: tools that escalate to recovery.
Sources
11 sources, checked by Julie Turnbridge on November 3, 2026
- Xero App Store apps.xero.com/uk/app/paidnice
- Capterra capterra.co.uk/software/254868/paidnice
- Xero App Store apps.xero.com/uk/app/chaser
- G2 g2.com/products/chaser/reviews
- G2 g2.com/products/credit-hound
- G2 g2.com/products/kolleno/reviews
- Xero App Store apps.xero.com/uk/app/kolleno
- Capterra capterra.co.uk/software/227932/Kolleno
- G2 g2.com/products/upflow-upflow/reviews
- Capterra capterra.co.uk/software/193097/Upflow
- Xero App Store listing apps.xero.com/uk/app/upflow