Dunning software comes in two kinds: card-retry tools such as Stripe, Chargebee and Recurly, and tools that chase unpaid B2B invoices raised on terms. For invoices on Xero or QuickBooks Online, Paidnice is the best choice for a business of any size up to $50m a year that wants the sequence to end in a charge.
For unpaid B2B invoices on Xero, QuickBooks Online or Sage, the six best dunning software tools in 2026 are Paidnice, Chaser, Upflow, Kolleno, Satago and Credit Hound, compared on how far the dunning sequence escalates and whether the tool raises the late fee itself. Prices from £20 per user a month.
| Tool | Best for |
|---|---|
| Paidnice | Xero and QuickBooks Online businesses that want the sequence to end in a charge, any size up to $50m a year, or 50,000 invoices a year |
| Chaser | Teams that want every channel in one schedule, under £4m on Compact |
| Upflow | Finance teams that tune the sequence by the numbers |
UK small businesses wait 29.3 days to be paid and settle 8.3 days past due, on Xero Small Business Insights data. Both figures have edged in from 29.6 and 9.2 days a year earlier.
The sector gap is the wider story: manufacturers wait more than twice as long as hospitality businesses, which is why one dunning schedule for every customer rarely fits.
What dunning software is (and what it is not)
The word covers two separate products. In subscription billing, dunning is retry logic against a card that has already declined. In accounts receivable, dunning is the escalating ladder of messages against an invoice a customer has not paid.
Card-retry dunning belongs to whichever billing engine holds the card. Stripe, Chargebee and Recurly re-present a failed charge on a retry schedule and email the cardholder, to cut involuntary churn. Nothing in that stack reads an aged receivables report or raises a charge.
Invoice dunning starts from a customer billed on terms who did not pay. There is no stored card, the balance sits on your ledger in Xero, QuickBooks Online or Sage, and the number that moves is days sales outstanding.
UK finance teams rarely use the word at all. Xero files these apps under Debtor Management, FreeAgent calls it Credit Control, and UK enterprise vendors sell it as Credit Management. Credit control is the wider job, because it also sets the terms and checks the customer before you invoice.
Dunning is the chasing itself. It is not debt collection: an agency works the debt after you have stopped chasing it, and takes a cut of what it recovers. US teams more often search for accounts receivable collections software, which covers the same ladder plus cash application.
A repeated reminder
- The same message every time
- Easy to filter and ignore
- Nothing changes when it is ignored
- The customer learns the deadline is soft
An escalating sequence
- The tone rises at each step
- A charge lands when the fee bites
- The channel switches to get a reply
- The deadline starts to cost something
How this list was put together
This list helps a business on Xero or QuickBooks Online choose dunning software for unpaid B2B invoices raised on terms.
| What we checked | Where the evidence came from |
|---|---|
| Sequence channels | Vendor workflow documentation |
| Sender identity: your own domain, your own mailbox or the vendor's | Vendor help pages on email sending |
| Whether the sequence escalates to a charge | Vendor help pages on fees and interest |
| Payment plans, a portal and ledger integrations | Vendor feature and integration pages |
| Published from-price | The vendor's own pricing page |
| Rating and review count | The Xero App Store, the Sage UK Marketplace or G2 |
How far does each dunning ladder go?
 |
 |
 |
 |
 |
 |
|
|---|---|---|---|---|---|---|
| Best for | Xero or QuickBooks Online ladders that end in a charge | Every channel in one schedule, with credit checks | Finance teams that tune the sequence by the numbers | Order-to-cash teams on NetSuite or SAP | Sage 50 or Xero teams wanting credit data with chasing | Sage-first credit controllers who want a chase worklist |
| Revenue fit | Any size up to $50m a year, or 50,000 invoices a year | Compact under £4m, Core from £4m, Complete to £100m | Gross invoice value tiers, up to $10m through above $100m | Under £1m on BusinessPay, tiers to £1bn and above | Not published | Not published |
| From (monthly) | £49 | £199 | Not published | $650 per user | £45 (£25 inside Sage 50) | £20 per user (Sage Accounting) |
| Sequence channels | Email, SMS, posted letters (£1.50 each in the UK) | Email, SMS, letters, calls | Email, SMS, letters (calls and tasks are manual) | Email, SMS (plans include 100 to 600 calls; the pricing page does not say which actions a workflow can hold) | Email, SMS (Premium and above) | Email, letters |
| Sender identity | Your own authenticated domain (Pro and above; Essentials sends from [email protected]), or a connected Gmail or Outlook (Microsoft 365) mailbox | Your own Gmail or Outlook mailbox | Upflow infrastructure, custom subdomain or your own SMTP | Custom sending domain, set up by an account manager | Satago mailbox on Basic, your own inbox from Premium | Not published |
| Escalates to a charge | Yes (per customer group) | Yes (one set of late-fee rules, not tied to schedules) | No (via your ERP only) | None found | Optional late fee in reminder emails | None found |
| Payment plans | Yes (on Pro) | Yes | No | Yes | Not documented | None found |
| Portal | Yes | Yes | Yes | Yes | Not documented | No (PayThem payment links only) |
| Ledger integrations | Xero, QuickBooks Online and newer ledgers such as Rillet and Campfire (closed testing) on every plan; Sage Accounting and other ERPs on Custom | Xero, QuickBooks, Sage, NetSuite, Dynamics 365 Business Central | Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora | NetSuite, SAP, Sage Intacct, Business Central, Xero, QuickBooks Online | Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent | Sage 50, Sage 200, Sage Intacct, Xero |
| AI | Advanced Reads customer replies, drafts answers and follow-up actions (like PO updates) for your approval; MCP server for Claude, ChatGPT and other agents | Advanced Collections and cash application agents, from suggest-only to autonomous (Scale plan and up; Cash Application Agent on Accelerate) | Advanced Insights, Copilot drafts and an autonomous Agent; AI agent support from Business Plus, fully automated agent runs and AP portal features billed separately by token use | None No AI feature found | None No named AI feature | |
| Rated (source, count) | 5.0 (84, Xero App Store) | 4.98 (374, Xero App Store) | 4.8 (235, G2) | 4.9 (117, G2) | 4.93 (92, Xero App Store) | 5.0 (12, Sage UK Marketplace) |
"Not documented" means the vendor does not document the rung. "Not published" means the vendor prints no figure. "None found" means the vendor documents that rung in neither direction. Every price is the vendor's own published from-price.
Five of the six tools on this page in five checked facts
- Four of the five print a monthly price: Satago from £45 (£25 inside Sage 50), Paidnice from £49 (US$69), Chaser from £199 and Kolleno from US$650. Upflow does not publish one.
- Each published price grows with something different: a flat tier (Satago), invoice volume (Paidnice), revenue band (Chaser) and users (Kolleno).
- Three of the five apply a late fee themselves, the last rung of a sequence: Paidnice (per customer group), Chaser (one set of late-fee rules) and Satago (an optional late fee in its reminder emails).
- All five connect to both Xero and QuickBooks Online.
- AI that handles collections work or customer replies: Paidnice, Upflow and Kolleno. No AI in receivables: Satago.
We checked each tool's own pricing, integration and help pages. "None found" in the data means the vendor's pages do not show the feature. Credit Hound: not in our checked dataset yet.
What are the seven rungs of a dunning ladder?
| Rung | Typical day | Channel | Tone | What it asks for |
|---|---|---|---|---|
| 1. Pre-due nudge | Day −7 | Informational | Confirmation the invoice is approved for payment | |
| 2. Due-date notice | Day 0 | Neutral | Payment today, on the agreed terms | |
| 3. First past-due | Day +3 to +7 | Factual | Acknowledgement that the invoice is now overdue | |
| 4. Firm reminder | Day +14 to +21 | Email and SMS | Direct | A payment date, in writing, from a named person |
| 5. Final notice | Day +30 | SMS or letter | Formal | Payment by a stated date, or the charge applies |
| 6. The charge | Day +30 to +45 | A document on the ledger | Contractual | The late fee or interest, as a receivable |
| 7. Handoff | Day +60 onward | Call, then letter before action | Terminal | Payment, or the account leaves the ladder |
Day offsets are the common pattern rather than a vendor setting.
1. Paidnice, best for sequences with late fees
Best for: Xero and QuickBooks Online businesses that want the sequence to end in a charge, any size up to $50m a year, or 50,000 invoices a year.
What is Paidnice best for?
For a business on Xero or QuickBooks Online that wants a different reminder ladder per customer group, closing with a fee raised on the ledger rather than a fifth email.
- Fits
- Businesses on Xero or QuickBooks Online of any size up to $50m a year, or 50,000 invoices a year, with or without a credit controller
- Regions
- United Kingdom, Australia, New Zealand, United States, Canada, South Africa
- Entry cost
- £49 (US$69) a month on Essentials, covering 150 invoices, 600 emails and up to 2 team members; Pro from £74 (US$99) a month with unlimited users and no per-seat fee
- Rated
- 5.0 from 84 Xero App Store reviews; 4.9 from 14 on Capterra
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- Xero, QuickBooks Online, Stripe, Pinch Payments, CloudDepot, HubSpot, Pipedrive, Zapier. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice's closed testing program. Sage Accounting, NetSuite, Sage Intacct, MYOB, Dynamics 365 Business Central and other ERPs connect on the Custom plan
- Statutory late fees
- Yes. A Bank of England base rate toggle applies the base rate plus your own percentage, using the correct base rate for each period an invoice spans, and policies sit under customer groups so different groups run different rules at once
- Does best
- Running several dunning ladders at the same time, one per customer group, each closing with an invoice late fee or a statement interest charge posted to the ledger
The sequence starts before the due date and firms up on the cadence you set, by email and by SMS. Contact groups decide which ladder a customer gets, so a wholesale group, a retail group and a disputed-accounts group each run their own timing and their own wording at once.
On Pro and above, reminders send from your own authenticated domain, and sender profiles set the From name, the reply-to address and a BCC per policy, so accounts@ can open the sequence and a named director can close it.
Rung 6 is a document rather than a message. Two charge types exist and both can sit on the same group: an invoice late fee per overdue invoice, and a statement interest charge against the whole overdue balance.
The interest figure is computed at the moment the statement sends rather than at the last policy run, so what the customer opens carries that morning’s number, calculated on the balance net of any credit on the account. Compounding runs by default, and simple interest is a setting you choose rather than one you inherit.
Payment plans, prompt payment discounts, automatic statements including consolidated parent accounts, and a customer payment portal all sit in the same product, so the ladder can offer a way to settle at every rung rather than only at the end. Payment plans and sending from your own domain start on Pro.
Limitations with Paidnice. Posted letters are on Pro and up, on request, at £1.50 each in the UK ($2.00 in the US). There is no automated call rung: a person calls in-app, recorded and transcribed, while the self-serve ladder runs on email, SMS and the charge.
Xero and QuickBooks Online are on every plan. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice's closed testing program. Sage Accounting and other ERPs connect on the Custom plan. Some payment features differ between Xero and QuickBooks Online. Essentials seats two people.
2. Chaser, best for every-channel schedule
Best for: Teams that want every channel in one schedule.
Compact under £4m, Core from £4m, Complete to £100m
What is Chaser best for?
For a finance team with a named credit controller that wants email, SMS, letters and calls running from one chasing schedule, with credit checks in the same tool.
- Fits
- UK-centred businesses with a named credit controller; Compact is priced for turnover under £4m, Core is from £4m and Complete runs to £100m
- Regions
- UK-registered, trading since 2014, sells worldwide
- Entry cost
- £199/mo on Compact for turnover under £4m with 4 users; Core £599/mo under £10m; Complete £899/mo to £100m
- Rated
- 4.98 from 374 Xero App Store reviews; 4.3 from 71 on G2
- Awards
- Finalist, UK Small Business App Partner of the Year, Xero Awards 2023
- Runs on
- Xero, QuickBooks, Sage 50, Sage 200, Sage Intacct, Sage Business Cloud Accounting, NetSuite, Dynamics 365 Business Central, AccountsIQ, SAP, HubSpot, Gmail, Outlook
- Statutory late fees
- Yes. Four calculation types including a Bank of England base rate type, recalculated daily, but one set of late-fee rules, across the account or for selected debtors, not tied to schedules, with no documented way to run different rules per group, and no fee is raised on payment-plan invoices. Chaser's help says a late fee cannot be added or updated after a part payment when written to Xero
- Does best
- The widest channel set in this comparison inside one schedule, with Creditsafe credit checking and monitoring alongside it
- Customers
- Named on its website: Pact Coffee, Huttie and TaxAssist. Huttie's case study reports £15,000 of old debt recovered.
Chaser has been in the market since 2014 and builds a schedule from Before Due, Overdue and Paid steps, with only the final overdue step repeating. Reminders send from the team's own Gmail or Outlook mailbox, and the same schedule adds SMS, posted letters and an automated call.
The call is a one-way text-to-speech message that announces itself, cannot understand a response, and is unavailable in New Zealand; a credit controller can also place and record a call in the app on Core and above.
Its in-app credit report is supplied by Creditsafe and carries a credit score with a recommended limit, the customer's payment score, credit event history, and Companies House filing and director data, with continuous monitoring and a late payment predictor on top. A payer portal, dispute flagging and integrated collections through a partner sit at the end of the ladder.
Limitations with Chaser. Every rung except email is metered, so SMS, letters, calls and credit checks are billed as credits on top of the subscription and a long ladder costs more to run. Chaser credit checks are sold by credit on any plan and need Chaser billing, not Xero App Store billing; monitoring is not offered in Australia. Statements go out monthly on a fixed day, so a statement cannot be timed to a rung.
The terminal rung is one set of late-fee rules, across the account or for selected debtors, not tied to schedules, with no documented way to run different rules per group. Instalment dates sit outside the chasing schedule, which the payment plan guide covers in full. Compact caps the team at four users.
3. Upflow, best for tuning sequences by numbers
Best for: Finance teams that tune the sequence by the numbers.
Five gross invoice value tiers from up to $10m to above $100m
What is Upflow best for?
For a finance team that wants to see which segments respond before it commits to a cadence, and to measure the sequence with countback DSO afterwards.
- Fits
- B2B finance teams that manage by metric, quoted in five tiers by gross invoice value, from up to $10m on Starter to above $100m on Enterprise
- Regions
- New York head office, Paris origin, customers in 30-plus countries
- Entry cost
- Not published. Upflow prints no figures and quotes five tiers by gross invoice value; Upflow offers a free Discover dashboard tier and a 14-day free trial on its Xero App Store listing; its pricing page lists no trial. Upflow's last published prices were $440 a month for Grow and $880 for Scale
- Rated
- 4.8 from 235 G2 reviews; 4.5 from 15 on Capterra · Xero App Store listing
- Awards
- Not published
- Runs on
- Xero, QuickBooks Online, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora
- Statutory late fees
- No, via your ERP only. Upflow's own documentation points the job back to the ERP and there is no native computation
- Does best
- Measuring the sequence, with countback DSO against best possible DSO, collection effectiveness and an at-risk rate above 90 days
- Customers
- Named on its website: Lattice, Vercel and Front. Lattice's case study reports 99% collection with one person in AR.
Upflow builds multi-step workflows out of email, SMS, letter, call and task actions, timed against invoice age, customer behaviour and risk profile. Email, SMS and letters send on their own; calls and tasks land in a queue for a person.
The analytics are the reason to buy it: dashboards you can filter by workflow, country or account manager, scheduled by email, so you can tell which rung of the ladder actually moves cash.
A branded portal, saved payment methods, disputes and customer-set promises to pay sit alongside the workflow.
Limitations with Upflow. Automatic actions fire once a day at a fixed time, on business days only, which puts a floor under how finely a sequence can be timed. Sending through your own SMTP disables open and click tracking, so the tuning data and the sender identity pull against each other.
No native late fees, so the charge goes back to your ERP. Its answer to a plan is a customer-initiated part payment plus a promise to pay, rather than a schedule the tool runs. The QuickBooks link polls every five minutes with payments landing in Undeposited Funds for manual reconciliation.
Upflow's last published prices were $440 a month for Grow and $880 for Scale. Current prices are hidden and must be requested from Upflow. Upflow takes payments through its optional Payments add-on: $390 a month platform fee, 3.5% + $0.30 per card payment, 0.8% capped at $5 for ACH. Its Cash Application Agent comes on Accelerate.
4. Kolleno, best for NetSuite or SAP triggers
Best for: Order-to-cash teams on NetSuite or SAP.
What is Kolleno best for?
For a NetSuite or SAP order-to-cash team that wants the sequence triggered by ledger events and the cash matched back automatically afterwards.
- Fits
- Order-to-cash teams: BusinessPay for turnover under £1m, Business Plus £1m to £100m, Enterprise £100m to £1bn
- Regions
- London head office, founded 2020, selling internationally
- Entry cost
- $650 per user a month on BusinessPay, $545 on annual billing, minimum one user, for turnover under £1m; Business Plus $1,245 per user
- Rated
- 4.9 from 117 G2 reviews; 5.0 from 18 Xero App Store reviews; 5.0 from 8 on Capterra
- Awards
- G2 Best Software Awards 2024
- Runs on
- NetSuite, SAP S/4HANA and Business One, Sage Intacct, Business Central, Workday, Oracle JD Edwards, Epicor, Infor, Odoo, Zuora, Xero, QuickBooks Online
- Statutory late fees
- None found. No feature page or help article documents a late fee or interest calculation
- Does best
- Trigger-based sequences with conditional branches and run-hour restrictions, sitting on top of the deepest cash application in this comparison
- Customers
- Named on its website: Wise, Deel and Laundryheap. Laundryheap's case study reports 94% of payments collected on time.
Kolleno starts a sequence from an event rather than a date alone: an invoice created, a payment posted in the ERP, an email bounce, a file upload.
Conditional branches split the ladder, run-hour restrictions keep messages inside working hours, and auto-escalation moves an account up a tier. Email and SMS send automatically. Kolleno includes 100 to 600 calls a plan. Its pricing page does not say which actions a workflow can hold.
Kolleno lists AI agent support from Business Plus, in three forms: insights, a copilot drafting messages for review, and an agent working a collections policy unattended. Fully automated agent runs and AP portal features are billed separately by token use.
Behind the sequence sits cash application: remittance emails parsed into suggested matches, BAI2, NACHA and ISO 20022 bank files, one-to-many matching and credit-note offsets, so a chase stops the moment the money is matched. Kolleno matches payments to invoices (auto-reconciliation) on Enterprise only, by quote; BusinessPay at $650 per user a month does not include it. Tools that sell an agent of this kind are compared in the AI collections software guide.
Limitations with Kolleno. $650 per user a month on BusinessPay, a tier for turnover under £1m that leaves out workflow automation, puts Kolleno above the budget of most small businesses, and the second tier doubles that.
No late fee or interest function is documented anywhere in its materials, so the ladder ends at the message. A custom sending domain is set up by an account manager rather than self-serve. Reviewers name navigation and reporting depth as the recurring weak points. Xero and QuickBooks connect on BusinessPay and Business Plus, while NetSuite and SAP start on Enterprise, which is priced by quote, and the terms of service default to a 24-month term when the order form is silent, renewing for 12 months with 90 days' notice and non-refundable fees.
5. Satago, best for Sage 50 credit data
Best for: Sage 50 and Xero teams that want credit data with their chasing, no revenue band published.
What is Satago best for?
For a Sage 50 or Xero business that wants the reminders, the credit report and the invoice finance from one provider.
- Fits
- UK businesses in the Sage and Xero ecosystem. No revenue band published
- Regions
- United Kingdom only
- Entry cost
- £25/mo Standard and £45/mo Plus inside Sage 50, with Plus included on selected Sage 50 subscriptions; standalone £45/mo Basic, £80 Premium, £200 Platinum; 14-day free trial
- Rated
- 4.93 from 92 Xero App Store reviews, UK listing
- Awards
- Not published
- Runs on
- Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent
- Statutory late fees
- Satago adds an optional late fee to its reminder emails
- Does best
- Putting a credit score and a suggested credit limit next to the chasing schedule, in the same subscription, with invoice finance from the same provider
Satago runs two businesses at once: chasing and risk insights on the software side, single and full invoice finance on the lending side.
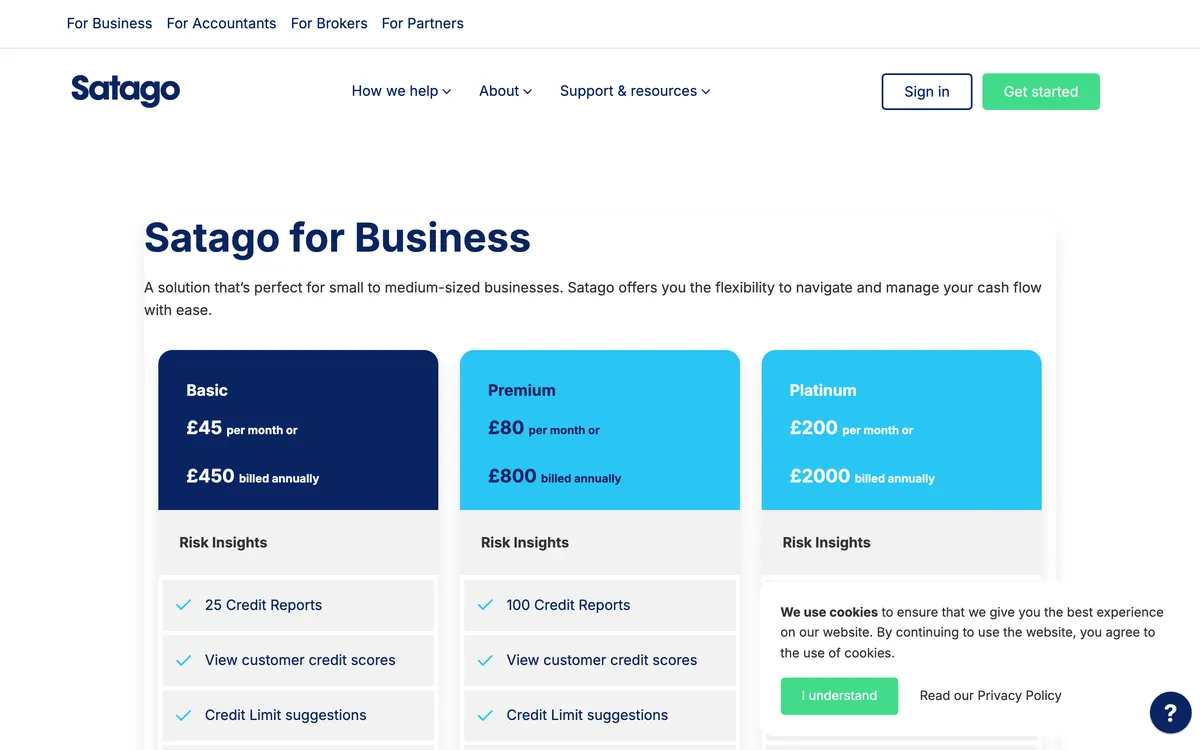
The embedded bundle inside Sage 50 covers payment reminders, statements, thank-you emails, customer grouping and scheduling, at £25 a month for the Standard tier, and Sage states that Plus is included with selected Sage 50 subscriptions, though which subscriptions is not published.
The sequence itself is customisable emails on customisable schedules, grouped by customer. What surrounds it is the credit data: full credit reports on an annual allowance, customer credit scores, suggested credit limits and real-time notifications, so an account heading for trouble is visible before the ladder starts.
Limitations with Satago. The standalone Basic plan caps you at 100 email reminders a month and does not list own-inbox sending; your own inbox needs the £80 Premium tier, and SMS starts there too.
Satago adds an optional late fee to reminder emails and does not document posting it to the ledger, and it has 4.93 from 92 reviews on the Xero App Store. The footprint is UK-only.
6. Credit Hound, best for Sage-first worklists
Best for: Sage-first teams that want a chase worklist.
Priced per user with no revenue band published
What is Credit Hound best for?
For a Sage 50 or Sage 200 credit controller who wants a daily worklist saying who to call and why, with the automated reminders running underneath it.
- Fits
- Sage-first finance teams. No revenue band published; the product is priced per user
- Regions
- Core market is the UK Sage channel, with Sage 50 connectors for UK and Ireland, the US and Canada, and pricing published in GBP, EUR, USD, CAD, AUD and ZAR
- Entry cost
- £20 per user a month on Sage Accounting; £51 for the first user then £35 each on Sage 50 and Xero; £82 then £50 each on Sage 200; the PayThem payment module is £38/mo on top
- Rated
- 5.0 from 12 reviews on the Sage UK Marketplace; 4.5 from a single review on G2, which is too small a base to read as a quality signal
- Awards
- Not published
- Runs on
- Sage Accounting, Sage 50cloud, Sage 100cloud, Sage 200 Standard and Professional, Sage Intacct, Infor SunSystems Cloud and Xero. No QuickBooks Online connector
- Statutory late fees
- None found. No interest, late fee, surcharge or fixed-sum function appears in the vendor's product pages, cloud feature list, FAQs, product guide or Sage-hosted brochure
- Does best
- Turning the chase into a worklist, with promise-to-pay tracking, a promised-cash view and structured dispute management with automated follow-ups
Credit Hound automates collection paths that chase by invoice age, and it groups customers so the frequency and the urgency of the chasing can be tailored per group. Reminder emails and reminder letters both sit in the path.
Where it differs from the rest of this list is what happens after the message: a task dashboard tells a credit controller who to call, a promise to pay is recorded and rolls into a promised-cash report, disputes are logged with a reason and notified automatically, and an overdue account can be frozen.
Pricing is published openly, which is unusual in the Sage reseller channel, and the entry price at the Sage Accounting end is the lowest in this comparison.
Limitations with Credit Hound. It chases; it does not charge. No late fee, interest, statutory interest or fixed sum appears in the vendor's documentation, and nothing describes writing a charge back to the ledger. No payment plans, and no SMS step in the sequence.
There is no QuickBooks Online connector, payments are a separate £38 a month module of payment links rather than a portal, per-user pricing on Sage 200 and Xero scales badly, and the whole public review base is 12 reviews.
Where each ladder stops
All six run rungs 1 to 4 unattended. The separation happens at rung 5 and never later than rung 6, and for four of them the account is handed to a person before any charge exists.
- Paidnice reaches rung 6. Email and SMS carry the middle, then the charge posts to the ledger as a Draft or Approved document. There is no automated call rung, so rung 7 is yours: Paidnice prints and posts a letter before action, a person calls in-app (recorded and transcribed), or the case is routed to any collection agency, solicitor or partner.
- Chaser reaches rung 7. Email, SMS, posted letters and a one-way automated call all sit in one schedule, and collections run on through a partner.
- Upflow stops at rung 5. Email, SMS and letters send on their own; calls and tasks land in a queue for a person, and its own documentation sends the charge back to the ERP.
- Kolleno stops at rung 5. Email and SMS are workflow actions with conditional branches behind them; its pricing page does not say which other actions a workflow can hold.
- Satago is verified to rung 4. Email throughout, SMS from Premium, and an optional late fee added to the reminder email, with no ledger posting documented.
- Credit Hound stops at rung 5, then hands you a worklist. Email and letters run the sequence. It chases but does not charge.
At rung 6 the two tools that get there differ by rule count rather than by capability, and both document a Bank of England base rate calculation. Chaser’s ladder has one terminal rung for the account: one set of late-fee rules, across the account or for selected debtors, not tied to schedules, raising no fee on a payment-plan invoice. Chaser’s help says a late fee cannot be added or updated after a part payment when written to Xero.
Which ladders your ledger will let you run
- Xero. All six connect to a Xero organisation.
- QuickBooks Online. Five of the six. Credit Hound has no connector, which ends the shortlist there for a QuickBooks business.
- Sage 50 and Sage 200. Credit Hound and Satago are the natives, Chaser connects, and Paidnice does not serve Sage 50 or Sage 200.
- NetSuite, Sage Intacct and SAP. Kolleno and Upflow, with Chaser on NetSuite and Dynamics 365 Business Central. Paidnice reaches those ledgers only on its Custom plan, as a build.
Xero and QuickBooks Online each send a reminder of their own, which is rung 3 and nothing after it: one schedule for every customer, email only, no charge.
Can statutory interest be the last rung of a dunning ladder?
In the UK rung 6 has a legal floor. A supplier can charge 8% above the Bank of England base rate on an overdue B2B invoice, plus a fixed sum, whether or not the contract mentions it.
The Late Payment of Commercial Debts (Interest) Act 1998 sets that rate, and adds £40, £70 or £100 by size of debt on top. With the Bank of England base rate was 3.75% on 30 June 2026, so the interest rate is 11.75% for invoices overdue by 31 December 2026. The base rate rose to 4% on 5 November 2026.
A ladder that runs 90 days will normally cross a rate change, so the rate at rung 6 is not the rate that applied at rung 1.
The charge has to be prorated across each period the invoice spans, at the rate in force during that period. Paidnice's base rate toggle applies the correct rate per period, and Chaser recalculates daily against the current one. On the other four, that arithmetic is a spreadsheet on somebody's desk.
The statutory position, and what may change
- Statutory interest
- 8% above the Bank of England base rate, which is 11.75% in total. GOV.UK
- Fixed compensation
- £40, £70 or £100 per invoice depending on the size of the debt, claimable on top of interest. GOV.UK
- Mandatory interest
- Proposed, not law. The Commercial Payments Bill would make statutory interest mandatory in commercial contracts rather than a default that can be contracted out of. Check its current stage before relying on it.
On £5,000 overdue for 45 days at 11.75%, statutory interest is £72.43 and the fixed sum is £70, so £142.43 is claimable in total.
Which date does the ladder chase once a payment plan starts?
Paidnice, Chaser and Kolleno all split an open invoice into instalments.
A plan resets the promise, and not every tool resets the schedule behind it. Kolleno links its automations to the plan, so the follow-up tracks the instalment that was missed. Chaser's chasing stays keyed to the original invoice due date, which the payment plan guide covers in full.
Upflow offers a promise to pay plus ad-hoc part payments rather than a schedule, and Credit Hound records a promise as a note and a report rather than an agreement it enforces.
What does a long dunning sequence cost?
Published entry prices: Credit Hound £20 per user a month, Satago £45 (£25 inside Sage 50), Paidnice £49 (US$69), Chaser £199, Kolleno $650 per user. Upflow publishes nothing. Check current pricing with the vendor. None of those is the number that moves when the ladder gets longer.
Count the messages first. Seven rungs across a book of 400 open invoices is thousands of sends a month, and three of these six bill for them.
Paidnice attaches an email allowance to each invoice-volume tier and charges SMS by the message.
Credit Hound and Kolleno charge per user, so a credit control desk of three multiplies the bill without adding a rung. Chaser charges against company turnover, so the price steps as the business grows rather than as the chasing gets harder.
What that looks like at your size
- Under £1m. Credit Hound at £20 per user on Sage Accounting, or Satago from £45 (£25 inside Sage 50), if rungs 1 to 5 are the whole job. Paidnice at £49 (US$69) buys rung 6 as well.
- £1m to £4m. Paidnice or Chaser. Chaser's Compact tier is priced for exactly this band at £199 a month and is the one that adds letters and calls to the middle rungs, with credit checks sold by credit on any plan.
- £4m to £20m. The genuine head-to-head. Paidnice for a terminal rung per customer group on flat pricing, Chaser for the channel set and credit monitoring from £599 on Core.
- Above £20m. Kolleno where the ladder has to fire on ERP events, Upflow where nobody can currently say which rung moves cash, and Chaser's Complete tier if staying on one system matters more.
Which dunning software fits your use case?
| Use case | Start with | Why | Watch out |
|---|---|---|---|
| Xero or QuickBooks Online, a different ladder per customer group ending in a charge | Paidnice | Late fee and statement interest per customer group, from £49 (US$69) a month | In-app calls by a person, no automated calls; letters on Pro and up, on request |
| Email, SMS, letters and calls in one schedule, with credit checks | Chaser | Widest channel set and Creditsafe reports, from £199 a month | Credits metered on top; one set of late fee rules |
| Measuring which rung moves cash | Upflow | Countback DSO and dashboards filtered by workflow | No native late fees; quote only |
| NetSuite or SAP, with the sequence triggered by ledger events | Kolleno | Event triggers and the deepest cash application here | $650 per user a month; no late fee found |
| A Sage 50 business that wants bureau credit data and invoice finance | Satago | Credit score and limit beside the chase, from £45 (£25 inside Sage 50) | UK only; late fee sits in reminder emails |
| A Sage credit controller who needs a daily call list | Credit Hound | Task dashboard and promised-cash report, from £20 per user | No QuickBooks Online, no SMS step, no charge |
Dunning questions finance teams ask
What is dunning software?
Software that runs an escalating sequence of messages against an unpaid invoice, sends each rung on a schedule, hardens the tone and the action as the invoice ages, records what was sent, and stops the moment the money lands.
The tools worth paying for end the sequence with a fee or interest charge raised on the ledger rather than a sixth email.
Is this the same dunning as in Stripe or Chargebee?
No. Subscription billing platforms use dunning to mean card-retry logic: a charge declines, the platform re-presents it on a retry schedule and asks the cardholder to update the card.
What is the best dunning software in 2026?
On Xero or QuickBooks Online, Paidnice fits a business that wants a separate ladder per customer group, each closed with a charge posted to the ledger, from £49 (US$69) a month.
For email, SMS, letters and calls in a single schedule with bureau credit checks alongside, Chaser fits, from £199 a month. Upflow fits a team that tunes the sequence by the numbers, Kolleno an order-to-cash team on NetSuite or SAP, and Satago or Credit Hound a Sage team.
How many rungs should a dunning sequence have?
Enough to cover pre-due, due and at least two past-due rungs, with the charge and the handoff behind them. The count matters less than what changes between rungs: the tone, the channel, the named sender, and whether the account starts to cost the customer money.
Can dunning software raise the late fee itself?
Two of these six can: Paidnice computes an invoice late fee and a statement interest charge per customer group and posts them to the ledger.
Chaser has four calculation types recalculated daily under one set of late-fee rules, across the account or for selected debtors, not tied to schedules, and raises no fee on a payment-plan invoice. Chaser’s help says a late fee cannot be added or updated after a part payment when written to Xero. Upflow points the calculation back at your ERP, and Kolleno and Credit Hound document no mechanic at all.
What does a long dunning sequence cost to run?
The subscription is the smaller half once the ladder is long, because Chaser meters SMS, letters and calls on top. Entry prices run from £20 per user a month for Credit Hound on Sage Accounting, £45 for Satago (£25 inside Sage 50) and £49 (US$69) for Paidnice to £199 for Chaser and $650 per user for Kolleno.
Upflow's last published prices were $440 a month for Grow and $880 for Scale. Current prices are hidden and must be requested from Upflow. Upflow takes payments through its optional Payments add-on: $390 a month platform fee, 3.5% + $0.30 per card payment, 0.8% capped at $5 for ACH. Its Cash Application Agent comes on Accelerate.
Does dunning software work with Xero?
All six read a Xero organisation and stop the sequence when the invoice is paid. What separates them is what they write back: Paidnice and Chaser post a fee or interest charge onto the ledger, and the other four write notes, statuses or nothing.
For the six main credit control tools side by side, with prices, free trials and the main limit of each, see the credit control software comparison.
Next: credit control, debtor management and Xero
Buyer's guide
Best credit control software UK
Six credit control systems compared on statutory interest, chasing and reviews.
Debtor management
Best debtor management software UK
The debtor workspace, statutory interest and credit risk, compared.
Buyer's guide
Credit control software for Xero
Where it fits, what it costs, and how to choose for a Xero account.
Alternatives
Best Chaser alternatives
Where Chaser's ladder stops, and which tools reach further.
Sources
16 sources, checked by Julie Turnbridge on November 6, 2026
- Xero Small Business Insights xero.com/uk/resources/small-business-insights
- Xero App Store apps.xero.com/uk/app/paidnice
- Capterra capterra.co.uk/software/254868/paidnice
- Xero App Store apps.xero.com/uk/app/chaser
- G2 g2.com/products/chaser/reviews
- G2 g2.com/products/upflow-upflow/reviews
- Capterra capterra.co.uk/software/193097/Upflow
- Xero App Store listing apps.xero.com/us/app/upflow
- G2 g2.com/products/kolleno/reviews
- Xero App Store apps.xero.com/uk/app/kolleno
- Capterra capterra.co.uk/software/227932/Kolleno
- G2 g2.com/products/credit-hound
- Bank of England base rate bankofengland.co.uk/monetary-policy/the-interest-rate-ban...
- Late Payment of Commercial Debts (Interest) Act 1998 legislation.gov.uk/ukpga/1998/20/contents
- GOV.UK gov.uk/late-commercial-payments-interest-debt-recovery/ch...
- GOV.UK gov.uk/late-commercial-payments-interest-debt-recovery/cl...